

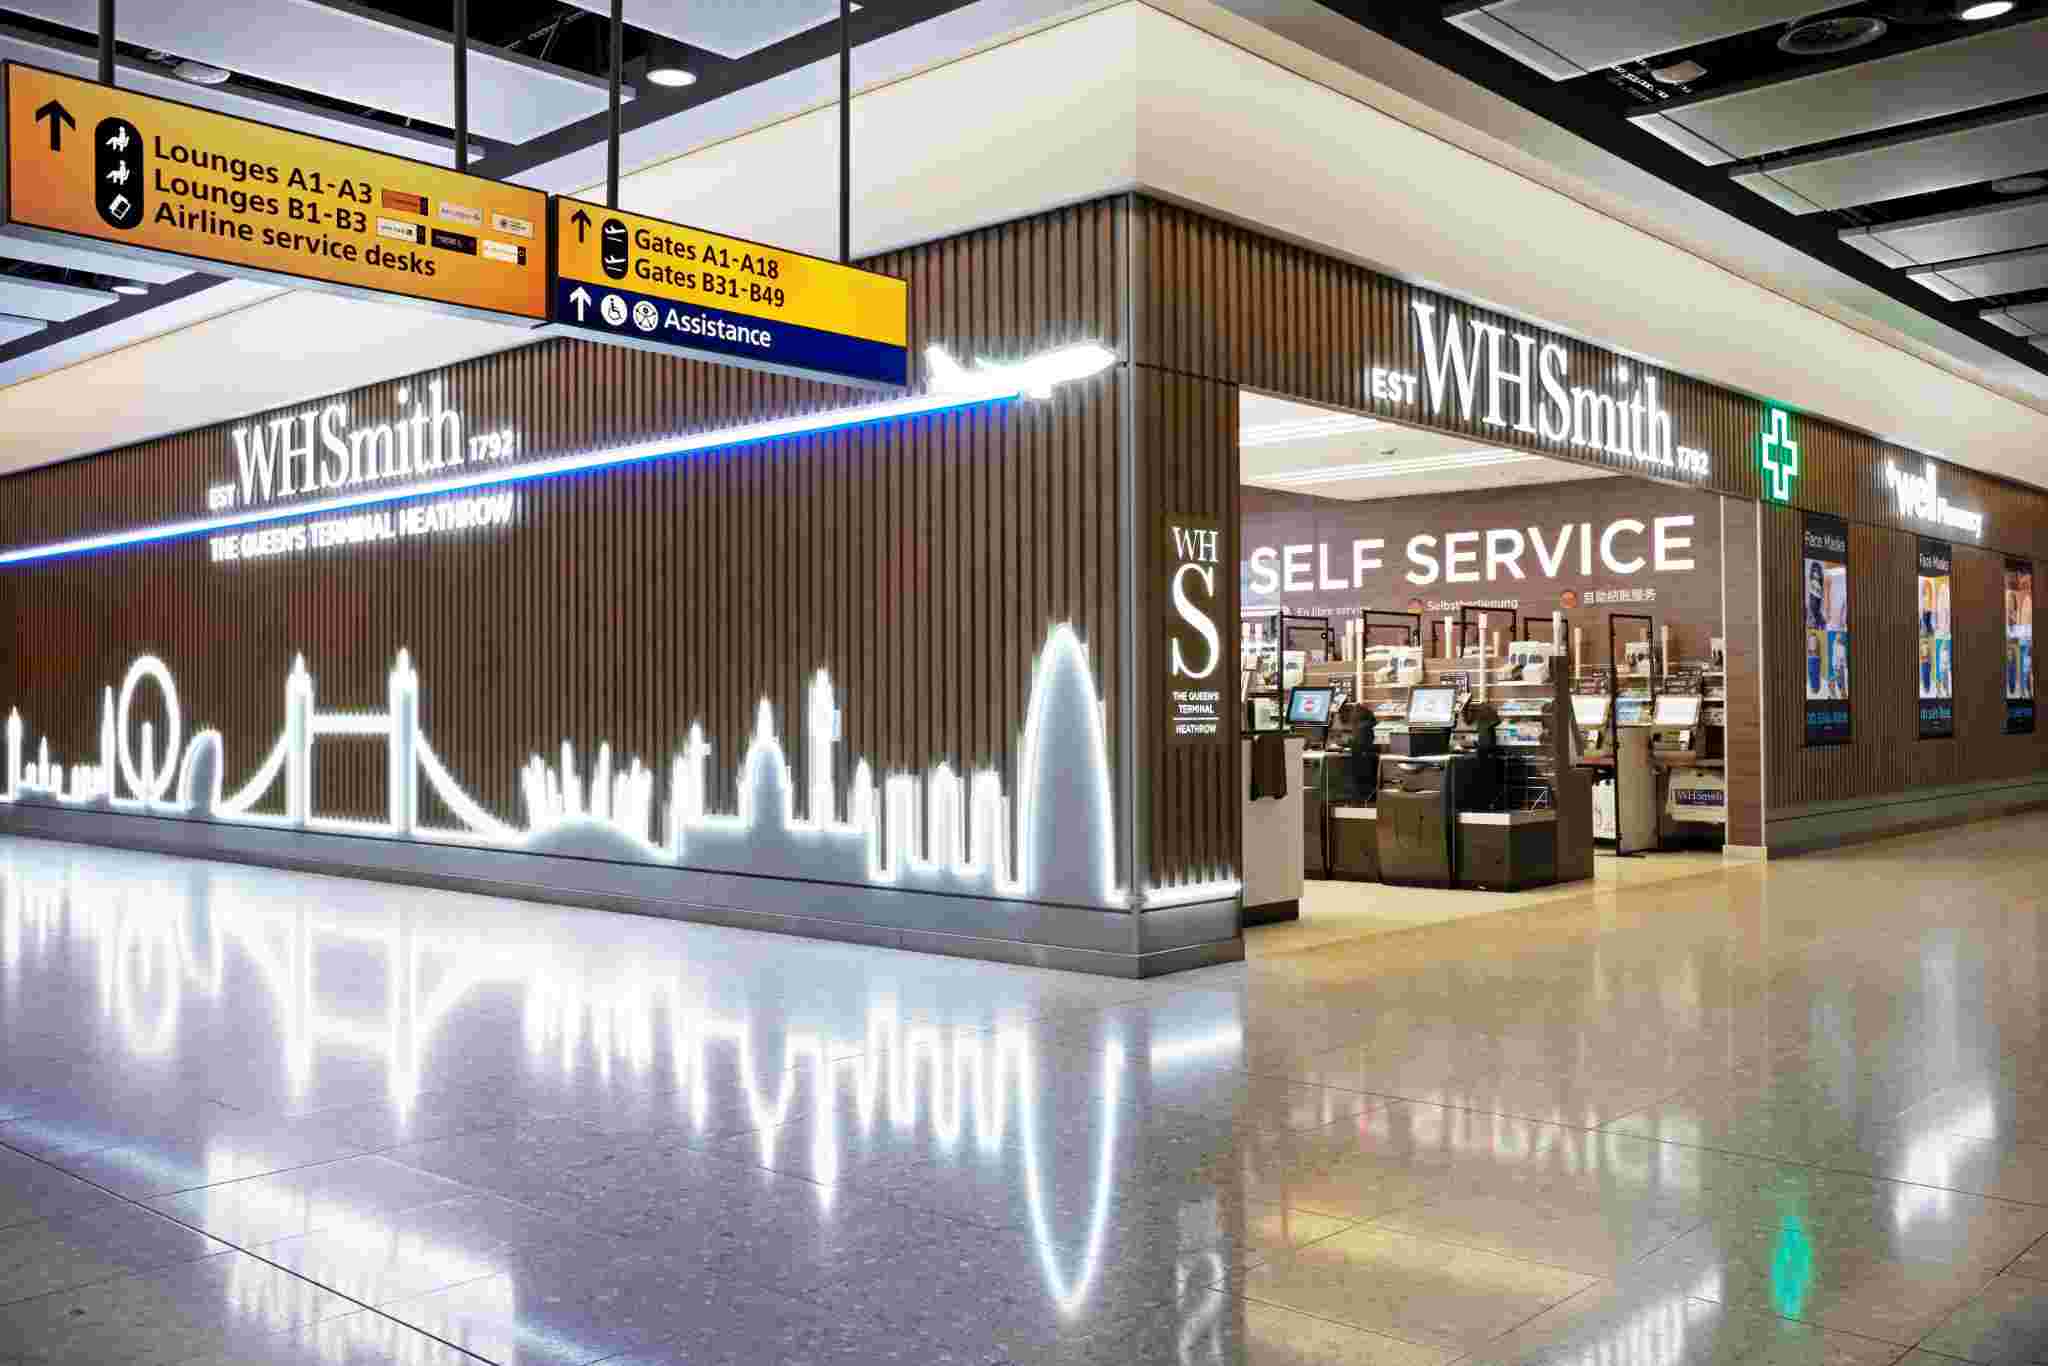
Shares in WH Smith (LON:SMWH) slid after the troubled travel retailer trimmed FY26 profit guidance. The FTSE 250 firm also reported a disappointing drop in North America like-for-like sales in Q4.
The latest downgrade overshadowed the ‘good progress’ that the embattled retailer is making with its transformation agenda.
Profit guidance trimmed
In a pre-close trading update, WH Smith said pre-tax profit for the year to August 2026 is expected to fall to roughly £75 million.
That is at the low end of the revised forecast given in June for taxable profits of between £75 million and £90 million. Fresh guidance also implies a year-on-year pre-tax profits drop of 30%.
WH Smith blamed the downgrade on lower trading margins from increased discounts, reduced brand marketing and inflation headwinds. These were partly offset by cost and interest savings, said the company.
North America disappoints
WH Smith described its Q4 revenue performance including the peak summer trading period as ‘solid’. This was certainly the case in the UK, where like-for-like sales rose 4% amid strong performances across UK airports, hospitals and train stations.
| Like-for-like sales vs 2025 | Q4 | FY26 |
| UK | 4% | 2% |
| North America | (3%) | 0% |
| Rest of the World and Other | 3% | 4% |
| Group | 2% | 2% |
Source: WH Smith, pre-close trading update
Unfortunately, North America like-for-likes decreased by 3%. This decline reflected lower year-on-year air passenger volumes in Q4, not helped by the Middle East conflict, air fare inflation and softer consumer demand.
In the Rest of the World division, total revenue in Q4 decreased by 4% as store closures continued, although like-for-like revenue was up 3%.
Shrink to grow
During FY26, WH Smith exited Norway and agreed to exit the Denmark and Sweden markets in early 2027.
The company will also exit the Netherlands on lease expiry in 2027 following a decision not to re-tender the contract. ‘This division is being actively managed both to exit unprofitable stores and transition sub-scale markets to a franchise model in order to improve profitability and cash generation,’ explained WH Smith.
Year-end net debt is expected to be around £325 million, with leverage around two times. That is in line with expectations following June’s £103 million equity raise designed to bolster the balance sheet and ‘capitalise on attractive growth opportunities across its key markets’.
WH Smith sold its UK high street arm to Modella Capital in 2025 in order to focus on its faster-growing travel retail division. Unfortunately, the business has been beset by problems since this strategic pivot.
Last year, WH Smith fessed up to overstating profits for its North America business, an accounting scandal which forced CEO Carl Cowling fall on his sword. And a series of profit downgrades and the suspension of the dividend have hammered the share price.
We believe it will be some time before confidence in the WH Smith story is restored. And given the potential for further downgrades, it feels too early to call the bottom in the stock just yet. Avoid.