

It’s tempting to give a one-word answer, but that would make this a very short article. In essence, valuation is the main attraction, but other factors also make the UK a rewarding hunting ground for activists. On the whole, UK companies are seen as well run, with good corporate governance, and are open to dialogue with major shareholders.
UK the most popular with activists
According to a study by investment bankers at Barclays (LON:BARC), the UK represents over half of the activist campaigns in Europe this year. Of the 28 campaigns aimed at companies with a market cap over $500 million (£375 million), 15 involve UK companies.
European activism by country year-to-date
| Country | 2026 Campaigns | 2025 Campaigns |
| UK | 15 | 13 |
| Germany | 2 | 4 |
| Ireland | 2 | 3 |
| Italy | 2 | 3 |
| France | 1 | 2 |
| Netherlands | 1 | 4 |
| Spain | 1 | 1 |
| Sweden | 1 | 0 |
| Switzerland | 1 | 0 |
Source: Barlcays, Bloomberg, FactSet, Dilligent Market Intelligence, 13D Monitor and publicly available sources
Across Europe, Industrial and Healthcare companies account for over half of activist campaigns this year. In the UK, companies in focus include Autotrader (LON:AUTO), Barratt Redrow (LON:BTRW), Bunzl (LON:BNZL), CVS Group (LON:CVSG), Intertek (LON:ITRK), LSE Group (LON:LSEG) and SEGRO (LON:SGRO).
Acivists typically target companies with a view to agitating for a sale or a break-up to ‘realise value’. In some cases, they will offer to acquire the company themselves, as in the cases of Intertek and Segro.
UK takeovers this year
When it comes to takeovers in the UK, asset managers and private equity firms have been the busiest participants at the bigger end of the market. Moving down the market cap scale, however, acquirers are more likely to be industry peers looking to increase share.
Financial services companies have been high on the list of UK targets this year as firms look to acquire technology, data and specialist capabilities. Hence Nuveen’s acquisition of Schroders, Zurich Insurance’s purchase of Beazley and NatWest’s (LON:NWG) purchase of Evelyn Partners.
Healthcare has also been in focus as innovation is increasingly driving valuations as well as growth. GSK’s (LON:GSK) purchase of Nuvalent and ELi Lilly’s (NYSE:LLY) purchase of Centessa highlight the race to find breakthrough therapies and future pipeline growth.
Current UK takeovers
| Target | Acquirer |
| Advanced Medical Solutions | HB Fuller |
| Aptitude Software | Unnamed |
| Ashtead Technology | Veritas Capital Mgmt |
| CAB Payments | Helios consortium |
| Capricorn Energy | DNO |
| Dianomi | Taboola |
| EasyJet | Apollo consortium |
| Eleco | Accel-KKR consortium |
| First Tin | Metals X |
| Futura Medical | Unnamed |
| Gamma Communications | Epiris consortium |
| Intertek | EQT consortium |
| Kore Potash | Unnamed |
| Logistics Development Group | DBAY Advisors |
| Mind Gym | Unnamed |
| Mitie | OCS Group |
| Mobico | Autobuses de Leon |
| NextEnergy Solar Fund | Unnamed |
| Pharos Energy | Ratio Petroleum |
| Pollen Street Group | Unnamed |
| Ramsdens | FirstCash Holdings |
| Rotork | ABB Ltd |
| SEGRO | Prologis |
| Spire Healthcare | Toscafund consortium |
| Sthree | Circle8 |
| System1 | Brave Bison |
| Tate & Lyle | Ingredion |
| Time Finance | Bentley Park |
| Tribal Group | Jenzabar |
| Vesuvius | RHI Magnesita |
Source: London Stock Exchange, Sharesify
M&A activity more concentrated
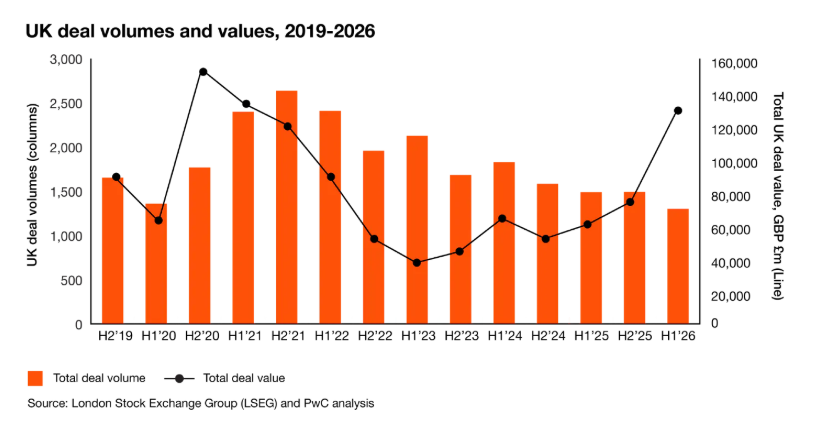
According to consultants PWC, M&A activity in the UK has become more concentrated in the last year. UK dealmakers deployed around £135 billion in H1 2026, more than double the amount committed in 1H 2025.
However, the number of deals has fallen by 13%, meaning more capital is chasing fewer deals. For company boards, the question is where is that capital concentrating and how can they compete for it.
Key takeaways for companies
PWC comments: ‘Capital is abundant. Conviction is scarce. Assets command a ‘concentration premium’ by demonstrating strategic coherence, sustainable differentiation, executable value creation and fitness for the future.’
Moreover, Agentic AI is creating ‘a new valuation divide’ say the consultants. Agentic AI can unlock revenue and drive margin but can also erode legacy profit pools. Therefore companies need an AI growth and mitigation strategy.
