

At-home beauty technology firm The Beauty Tech Group (LON:TBTG) posted H1 results which beat expectations across the board. In addition, with a seasonally strong H2 in prospect, the company raised its adjusted EBITDA guidance for the full year.
Revenue and margins beat expectations
For the six months to June, the group increased revenue by 44% to £79.7 million. The at-home category is growing at a much faster rate than the wider beauty market yet still represents just 1% of beauty spending.
Gross profit, which is earnings after the cost of sales, rose 53% to £51.3 million. That represented an H1 gross margin of more than 64% against around 61% in H1 2025.
Adjusted EBITDA also rose 53% to £21.3 million, representing a margin of nearly 27% against 25% previously. This continues the company’s record of growing its margins faster than sales over the last five years.
The Beauty Tech Group H1 results
| H1 2026 | H1 2025 | Change | |
| Revenue (£m) | 79.7 | 55.2 | 44% |
| Gross profit (£m) | 51.3 | 33.6 | 53% |
| Adj EBITDA (£m) | 21.3 | 13.9 | 53% |
| Adj pre-tax profit (£m) | 15.3 | 10.3 | 49% |
| Adj EPS (p) | 10.4 | 7.0 | 49% |
Source: Company accounts
The global market opportunity
The global at-home beauty device (AHBD) market is estimated to be worth between £9 billion and £12 billion annually. However, that is still only 1% of total beauty spending according to a 2025 report.
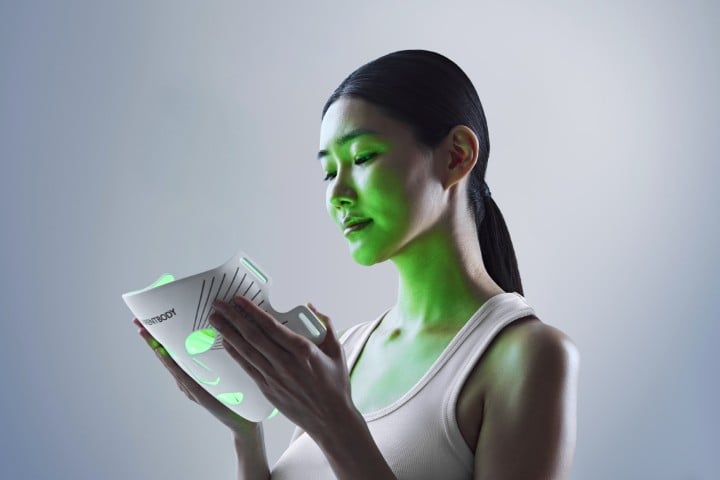
Beauty Tech Group has three brands, each with its own product pipeline, of which the biggest by far is CurrentBodySkin. Seven years after the launch of its first mask, demand is still acccelerating with H1 sales up 45% to £71 million.
Sales of the firm’s second brand ZIIP Beauty rose 26% to £7 million, while a ‘significant’ programme of product launches is planned for H2 to renew the brand. Tria Laser, the third brand, is still in its early growth phase and delivered a 166% increase in revenue to £1.6 million.
Positive outlook, strong balance sheet and share buyback
Group sales are typically weighted to H2 and especially Q4, which includes Black Friday and Christmas. Margins are also typically higher in H2, therefore EBITDA is likely to exceed previous guidance. The firm now sees FY EBITDA of no less than £48.5 million compared to its previous target of £45 million.
As of 30 June, the group had zero debt and £52 million of net cash on the balance sheet, equivalent to 14% of its market cap. Thanks to the positive outlook and its financial strength, the company has launched a £20 million share buyback.
This is our fifth write-up of Beauty Tech Group in nine months, and we continue to like the company. Not just for the ‘beat and raise’, which most people will focus on, but for the long-term potential of the technology.
As founder and CEO Laurence Newman says, he started the business based on a simple belief. He could see clinical devices used in high-end beauty clinics eventually being miniaturised for use in the home.
For the last five years, the at-home market has been the fastest-growing part of the overall beauty market. Yet it still represents a drop in ocean compared to total spending, and Beauty Tech Group has the leading brands.
It has invested heavily in product development and safety, and continues to invest in clinical studies and new technology. It has also invested in its own manufacturing capability and is even building its own testing laboratory.
Being a new listing (October 2025), we can’t run the company through our CAPE valuation model as we would normally. However, analysts at Berenberg argue the shares are ‘far too cheap’ on a 2026 P/E of 11.7 times, a 50% discount to the group’s most direct peers.