

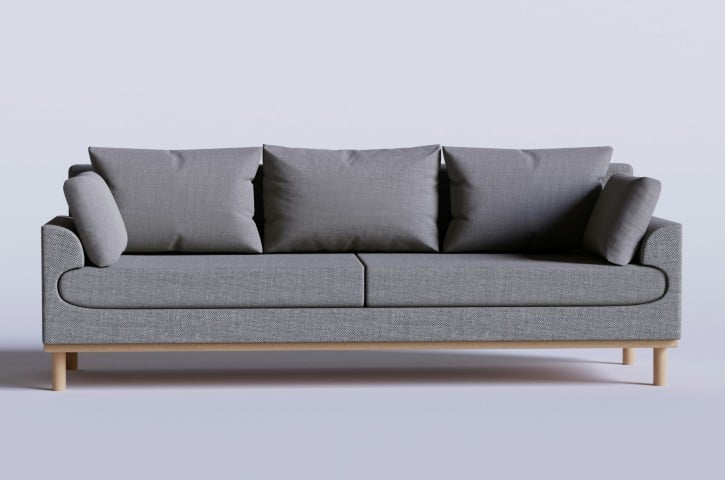
Shares in DFS Furniture (LON:DFS) tumbled after the sofa seller warned that upholstery market demand has softened further over the past seven weeks.
Against a backdrop of fluctuating footfall and fragile consumer confidence, DFS cautioned that FY27 profit expectations ‘naturally carry a wider range of potential outcomes’.
Investors read this increasingly cautious outlook as a profit warning and marked the shares down in early dealings.
Further slowdown in demand
In an update ahead of its AGM (annual general meeting), the Doncaster-headquartered retailer said upholstery market demand weakened further in the seven weeks ended 8 November.
Led by CEO Tim Stacey, DFS has not been immune from this downturn in demand, which reflects ongoing pressure on household budgets and reduced consumer confidence.
Before this further weakening, the specialist retailer had reported a 2.5% year-on-year decline in order intake for the first 12 weeks of FY27.
Core brands outperform
On the positive side of the ledger, Lloyds banking data covering 14 specialist upholstery retailers indicates that the group’s core retail brands, DFS and Sofology, have continued to outperform the wider sector.
This outperformance reflects the resilience of Britain’s leading sofa seller, which has historically emerged from furniture industry downturns with increased market share. In this tough environment, DFS said it is investing to support customers with targeted commercial initiatives to drive conversion during Black Friday and its Winter Sale.
Controlling the controllables
‘While the consumer environment has remained challenging through the autumn, DFS is well placed within it as the clear market leader with unmatched scale, brand resonance and operational strength,’ insisted Stacey.
‘As we enter the important upcoming trading periods, we are focused on what we can control; taking proactive commercial actions to drive cash margins while maintaining tight control of our costs.’
Shore Capital reiterated its Buy rating on DFS, albeit with a price target downgrade to 180p. The broker commented: ‘While we do still see our long-term thesis on DFS as robust, a further softening of the market backdrop will justifiably increase investor caution in the company.’
We are admirers of DFS Furniture, which has significantly strengthened its balance sheet in recent years and returned to the dividend list. Under Stacey’s stewardship, the company is outperforming a subdued market whilst keeping a lid on costs.
When consumer confidence and the housing market do recover, the operational leverage in the business should drive bumper profit growth. Unfortunately, soaring energy bills, higher taxes and a recent 0.25% rise in UK base rates look set to crimp spending on big-ticket purchases. And these items include sofas, beds, mattresses and living room furniture.
While DFS has yet to formally downgrade guidance, and the shares look cheap on a single-digit multiple of forward earnings, forecast risk is firmly to the downside. On that basis, we would avoid the shares for now.
