

Shares in Fevara (LON:FVA) firmed after the livestock supplements specialist said FY26 profits will top market expectations. Adjusted EBIT is now expected to be around 60% higher year-on-year thanks to broad-based growth across the UK, Europe and US.
Fevara said trading through the first few weeks of FY27 has been ‘encouraging’. And management reiterated its medium-term targets. These include growing revenue to £120 million and adjusted EBITA to £15 million, as well as delivering a 20% return on capital employed (ROCE).
What does Fevara do?
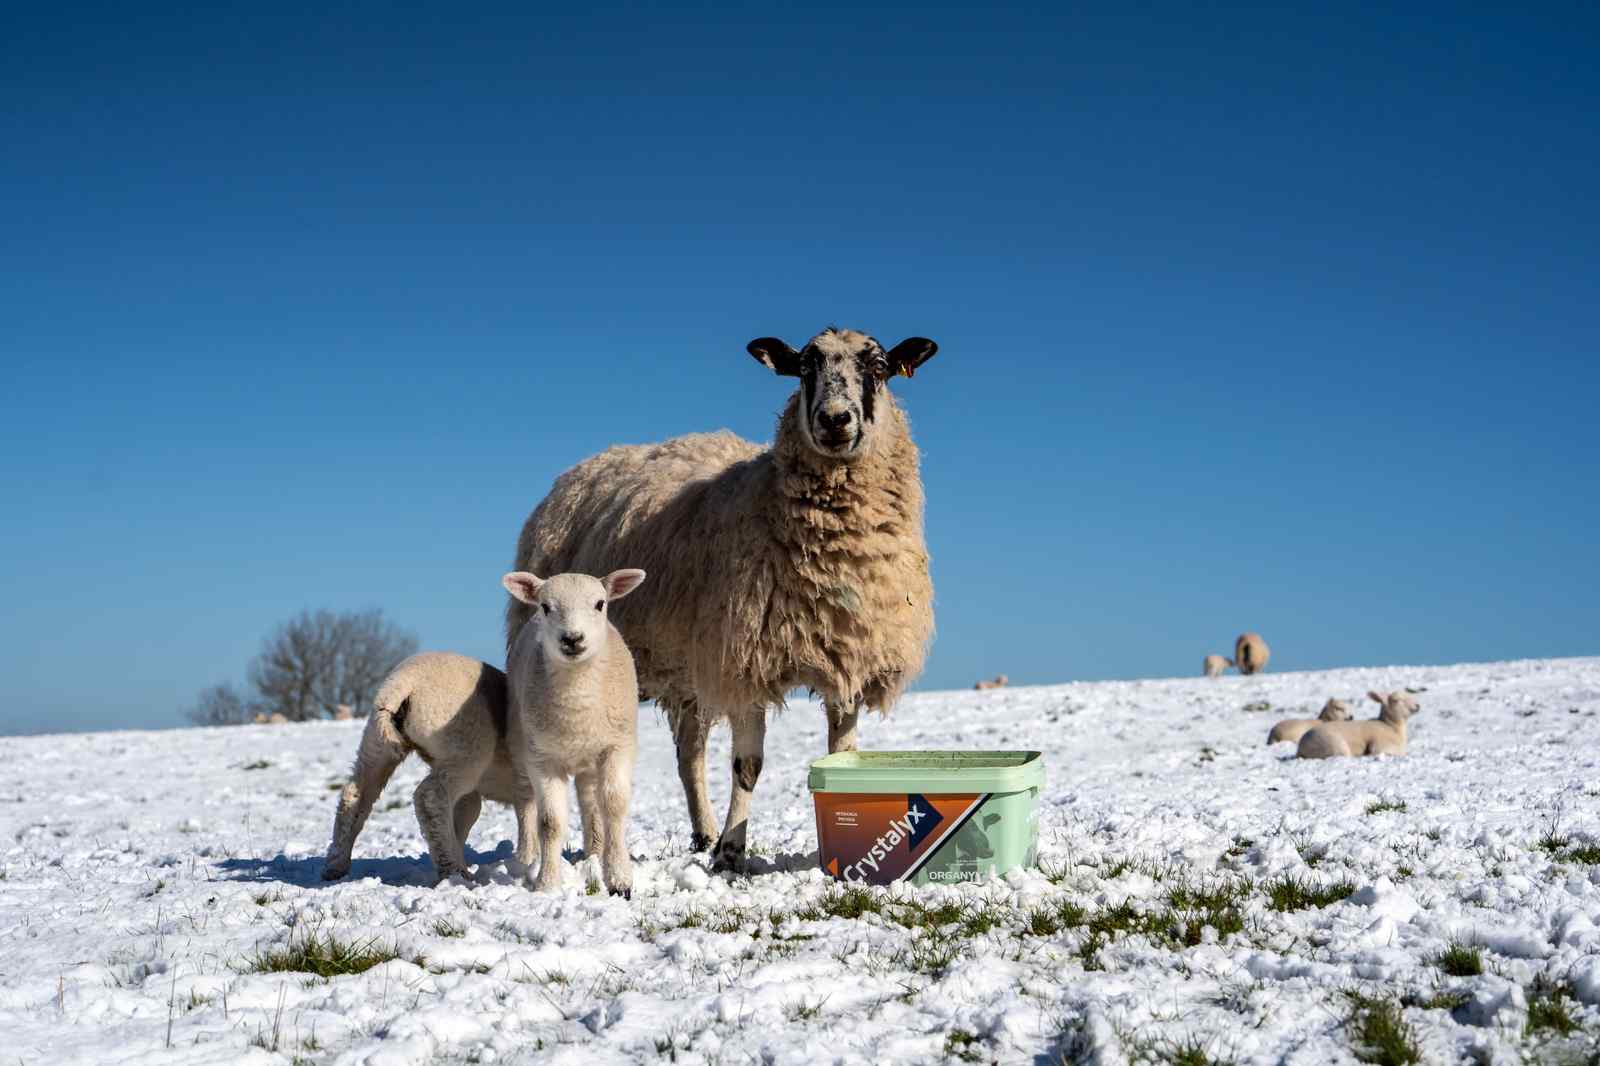
Fevara serves farmers in the UK, Ireland, US, Germany, Canada and New Zealand with high-quality feed blocks and feed supplements. Its unique products can be used in all weather conditions to improve the health, performance and profitability of livestock.
Sharesify highlighted the company’s tasty global growth potential here in May. Our interest was piqued by the firm’s first foray into Brazil, the world’s largest beef producer.
60% earnings surge
For the year to August 2026, Fevara expects to report revenue of around £86 million. That represents 8% like-for-like growth year-on-year. In addition, adjusted EBIT is now expected to exceed market expectations at approximately £6 million, marking 60% year-on-year growth.
| Year to August | FY25A | FY26E | FY27E |
| Revenue (£m) | 78.8 | 85 | 96 |
| EBIT (£m) | 3.7 | 6 | 7.3 |
| EPS (p) | 3.5 | 8.5 | 13.5 |
Source: Company accounts, Canaccord Genuity estimates
During FY26, Fevara’s UK, European and US businesses all performed well with sales of low moisture blocks delivering continued growth.
What did the CEO say?
CEO Joshua Hoopes said he is confident his charge is well positioned to capitalise on the ‘significant’ growth opportunities ahead.
‘Across the business, our teams have worked hard to deliver on all fronts across our strategic pillars as we continue to develop our leading position as an international specialist for livestock supplements,’ said Hoopes.
‘During the year, we have completed a number of significant milestones, including the completion of our strategic refocusing, the delivery of corporate simplification initiatives, further enhancing our portfolio through new product launches and, perhaps most significantly, our entry into the important Brazilian market.’
We have a positive stance on Fevara. Following the recent disposal of engineering business Chirton, the company is fully focused on international livestock supplements. Furthermore, the balance sheet has been strengthened and there is tasty growth potential in Brazil.
Following today’s update, Canaccord Genuity reiterated its buy rating and 190p price target. The broker believes the current valuation ‘does not fully reflect Fevara’s improving profitability, strengthened balance sheet and significant long-term growth opportunity in all its geographies but particularly in Brazil.
‘Successful execution of the Brazilian strategy, together with further margin expansion and disciplined M&A, provide scope for additional upside over the medium term.’