

Shares in Greggs (LON:GRG) rallied after the food-to-go retailer reported an acceleration in Q3 like-for-like sales and delivered an unexpected profit upgrade. Thanks to its improved trading performance in recent months and strong cost control, the sandwiches-to-sausage rolls seller now expects a ‘modestly improved’ outcome for FY26. Previously, Greggs had guided for flat pre-tax profits year-on-year.
Investors also welcomed news that Greggs plans to consolidate its in-house manufacturing operations. The closure of four manufacturing sites should result in annual savings of roughly £20 million across the FY28 and FY29 financial years.
Improving trend
Company-managed shop like-for-like sales grew 3.4% for the 13 weeks to 26 September 2026. Greggs attributed this improved trading to the successful launch of new products and more settled weather in August and September.
Year-to-date, total sales are up 7.4%. And like-for-like growth is running at 2.6%, respectable enough given prevailing tough food-to-go market conditions.
| Year to December | FY26E | FY27E | FY28E |
| Revenue (£m) | 2,317.7 | 2,484.8 | 2,667.5 |
| Pre-tax profit (£m) | 180 | 183.8 | 203 |
| Dividend per share (p) | 69 | 69.9 | 73.3 |
Source: Investec Equities estimates
Investec upgraded its FY26 pre-tax profit forecast by 4% to £180 million. For the time being, the broker is sticking with its FY27 pre-tax profit forecast of £183.8 million, ‘given that there may well be some disruption from the proposed consolidation as well as increasing caution on the consumer environment outlook’.
Over the summer, Greggs saw strong demand for its iced drinks range, while the relaunch of its salads drove ‘encouraging’ sales growth. ‘We have also seen continued momentum in sales of healthier and protein-led options, supported by the expansion of our functional drinks range,’ added the cut-price coffees-to-sweet treats purveyor.
Hungry for market share
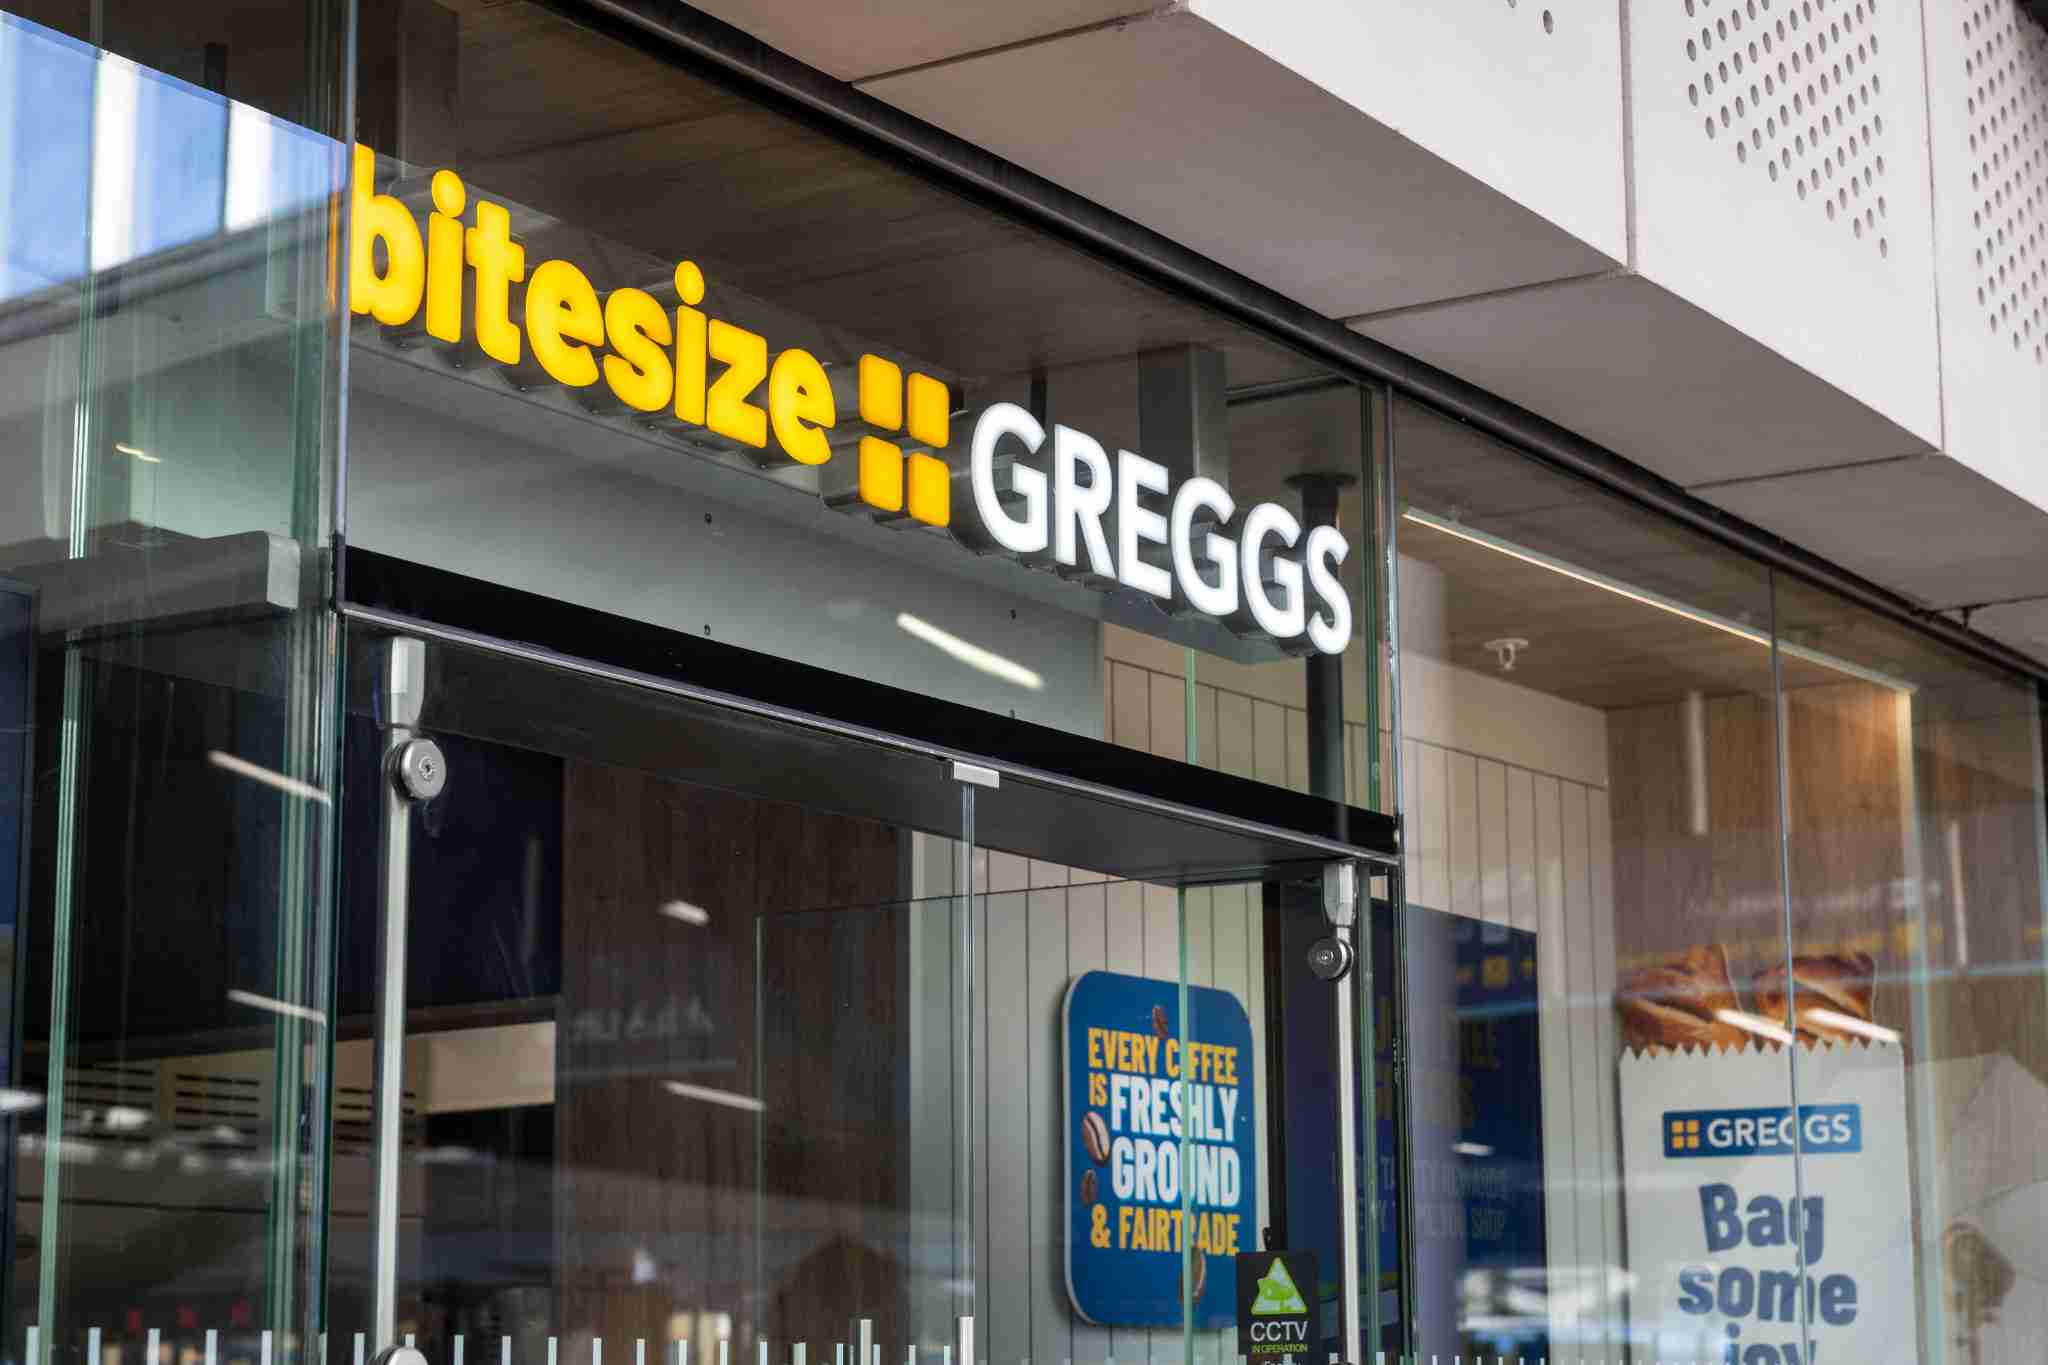
Openings in Q3 included Greggs’ fifth ‘bitesize Greggs’ at the Tesco Southwark Superstore and its 50th drive-thru site, in Sunderland.
‘The initial trading performance of new shops opened in 2026 is strong, reflecting our disciplined focus on high-quality locations,’ said Greggs. ‘For the year as a whole, we continue to expect around 100 to 110 net new shop openings.’
Albeit modest, the upgrade to FY26 guidance is welcome and attests to the resilience of this beloved British food brand.
Under CEO Roisin Currie, Greggs continues to deliver share gains in a challenging food-to-go market. Clearly, the Newcastle-based company’s value offer is still resonating with cash-strapped consumers.
We reiterate our view remains that fears over ‘peak Greggs’ are overdone and there is still a tasty growth opportunity ahead. The FTSE 250 firm currently trades from a total of 2,796 shops. And management sees a clear opportunity for ‘at least 3,500 UK shops’ over the longer term.
Investec points out Greggs is past its peak distribution capex. This means it should start rebuilding its net cash position in FY26 ‘with the prospect of enhanced returns from FY27E’.
The broker believes: ‘Business momentum should increase confidence in management’s ability to rebuild return on capital employed (ROCE) towards its targeted 20% as it leverages recent investment.’
Disclaimer: The author (James Crux) owns shares in Greggs.