

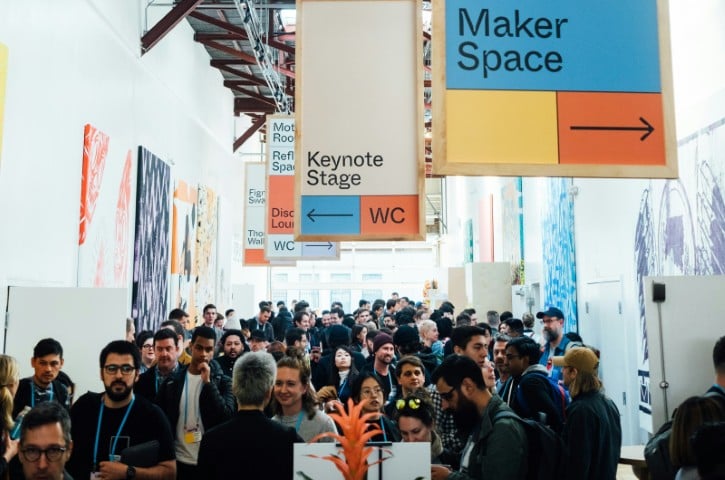
Events and publishing firm Informa (LON:INF) announced a strategic shift with the acquisition of Clarion and a review of its academic business. The move will increase the group’s focus on B2B (business-to-business) activities and generate revenue and synergy opportunities.
Acquisition of Clarion Events
Informa has agreed to acquire Clarion Events from US asset manager Blackstone for £3.24 billion including debt. Clarion has over 100 clients including eight ‘marquee’ brands generating $30 million-plus of revenue, and should add around £575 million of sales next year.
As well as bringing in revenue, the Clarion deal adds further depth in North America and Asia and ‘significantly’ strengthens Informa’s European presence. It also brings exposure to three high-growth categories: electronics, defence and security, and gaming.
In order to finance the purchase, Informa is raising £940 million in an institutional share placing with an additional offering for retail investors. The firm has also stopped its current share buyback to divert funds towards the acquisition.
In 2025, Informa’s live events business generated sales of £3 billion or 75% of the group total. Most of the remaining 75% came from the Taylor & Francis academic publishing business, while digital services contributed less than 10% of sales.
Review of the academic business
Alongside the Clarion deal, Informa announced it wouold separate out the Taylor & Francis academic business. It described the move as ‘providing greater independence and flexibility to support its future ambitions for growth, academic discovery and societal impact’.
Since Taylor & Francis joined Informa in 2004, the division has increased its revenue four-fold. By comparison, B2B revenue has risen 10-fold since 2014 and now dwarfs the academic division.
CEO Stephen Carter commented: ‘With Taylor & Francis approaching $1bn in revenue, growing at 4% and with its Open Research capabilities firmly established, we believe it will now benefit from greater flexibility and freedom through the next phase of its development, as Informa further expands the depth and reach of its B2B portfolio.’
Informa used to a ‘market darling’, and its shares more than quadrupled in the decade leading up to Covid. With the complete absence of in-person events, revenue obviously tumbled and the shares collapsed.
That proved to be a great buying opportunity, as it did with a lot of stocks, and the shares are now comfortably higher. For the next stage in its journey, the group is doubling down on the live events business.
Buying Clarion increases its geographic footprint and adds new markets and clients to its roster. It is also expected to deliver mid-single-digit EPS growth from 2027 and a double-digit return on capital by 2029.
We don’t have a strong opinion on the company, but we imagine investors will be happy enough with today’s news. The fact the shares are up ahead of a 9% dilution through a new share issue would seem to confirm that view.