

AIM-listed compound semiconductor wafer maker IQE (LON:IQE) raised its FY26 revenue guidance citing ‘upside opportunities’ in optical communications. The firm now expects sales to grow by over 40% from a previous forecast of over 30% growth.
‘Upside opportunities’ for revenue growth
The Cardiff-based company raised its revenue growth outlook in a trading update for the year to December. Having previously raised its forecast to ‘in excess of 30%’, the firm now sees sales growth exceeding 40%.
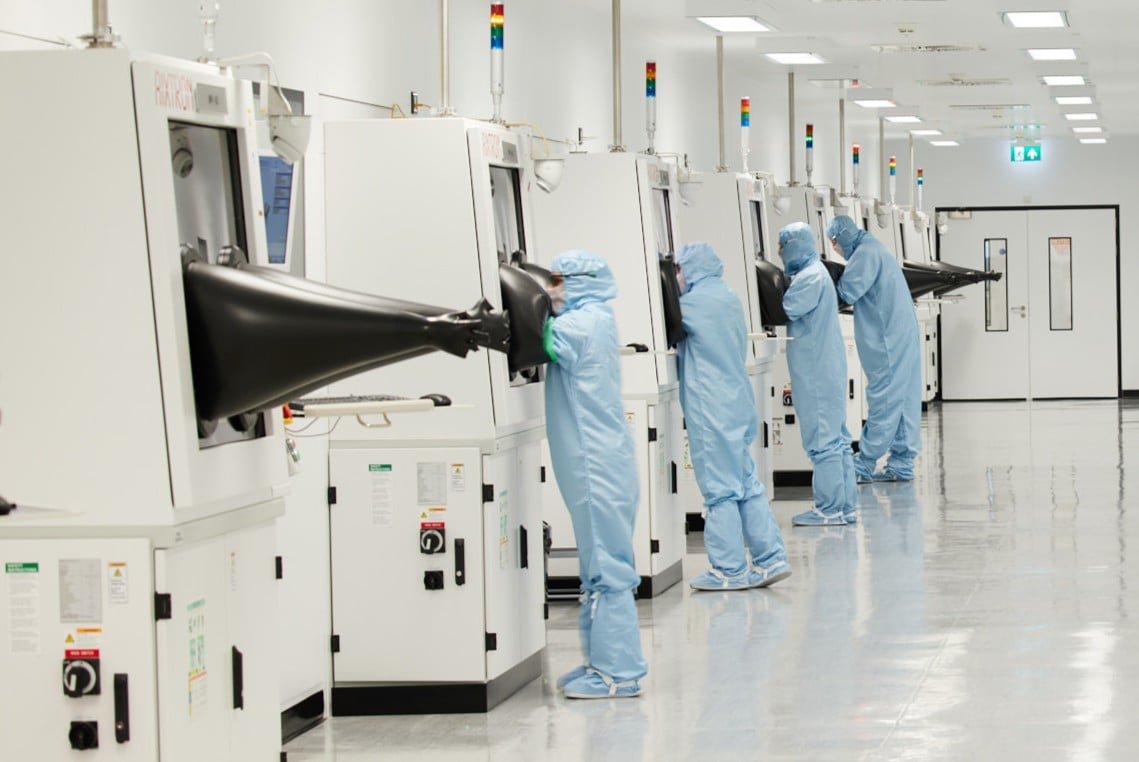
The firm based the increase on ‘upside opportunities’ in optical communications for datacentre and AI infrastructure markets. IQE supplies advanced compound semiconductor wafers and materials for consumer electronics, communications equipment, aerospace and defence, automotive and industrial uses and datacentres.
As well as raising its revenue guidance, the firm said adjusted EBITDA would be in the ‘mid-teens’ millions of pounds rather than ‘low teens’. The upgrades come after the group signed new supply agreements, providing greater visibility and better factory utilisation.
What did the CEO say?
Chief Executive Jutta Meier commented: ‘The continued strength of our performance reflects IQE’s critical role in enabling the rapidly-growing AI and datacentre infrastructure market.
‘The conversion of previously identified opportunities into revenue while maintaining disciplined operational execution across the Group has enabled us to upgrade our full-year outlook once again.
‘With strong order book coverage already in place for 2027, we are well positioned to build on this momentum and capitalise on the opportunities ahead.’
IQE had an incredible start to 2026, with the shares jumping more than 10-fold in just over four months. Since then, they have drifted lower on profit-taking but they are still up more than five times since January.
Despite its impressive sales growth, the firm made a pre-tax loss at the H1 stage. That’s unlikely to change for now, although a mid-teens FY EBITDA would mean it made around £10 million in H2 against £6 million in H1.
Net cash flow dropped sharply in H1 as a result of £2.4 million of restructuring charges and £4 million of working capital requirements. While the first shouldn’t recur in H2, more orders mean more working capital, such is the nature of the business.
The firm is looking to move to the Main Market at some point in H1 2027. Hopefully that will raise its profile with large investors and improve liquidity in the shares.
