

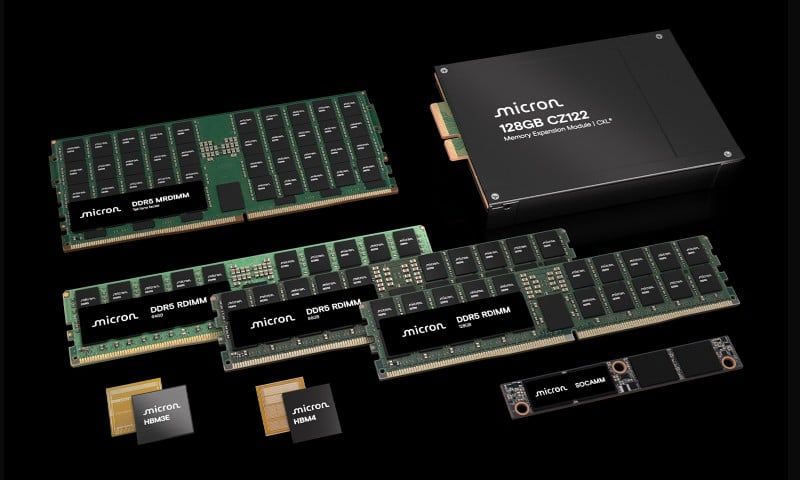
Positive results overnight from US memory chip maker Micron (NASDAQ:MU) failed to lift sentiment towards European tech stocks. Semiconductor maker STMicroelectronics (EPA:STM) and equipment maker ASML (AMS:ASML) opened higher, but quickly gave up their gains.
Q4 results beat market expectations
Micron reported stronger-than-expected Q4 results, thanks to the continued surge in demand for memory chips. Revenue of $54.2 billion was nearly five times the prior-year figure and well above the $51.2 billion consensus.
Earnings per share of $33.42 were more than 11 times the prior-year figure of $3.03 and also well above the $31.60 consensus. Despite the beat, however, Micron shares dipped slightly in after-hours trading.
The firm said revenue from the cloud memory business increased to $16.3 billion from $4.5 billion a year earlier. Meanwhile, data centre revenue soared to $18 billion from $1.6 billion and mobile and client revenue jumped to $13.1 billion from $3.8 billion.
Micron Q4 2026 results and Q1 2027 guidance
| Q4 FY26 Forecast | Q4 FY26 Actual | Q1 FY27 Forecast | |
| Revenue ($bn) | 51.2 | 54.2 | 60-63 |
| EPS ($) | 31.60 | 33.42 | 38.15 |
Source: Micron Technology
Q1 FY27 forecasts top consensus
For Q1 FY27, the company forecast revenue of between $60 billion and $63 billion. The current consensus according to FactSet is for Q1 sales of $57.4 billion.
In terms of earnings, the firm is predicting $38.15 per share against a FactSet consensus of $35.47. Micron CEO Sanjay Mehrotra said ‘as strong as FY26 was, we expect FY27 to be even better’.
Mehrotra added: ‘Industry demand has strengthened since our last earnings call, and we expect memory and storage supply-demand conditions to be much tighter in fiscal 2027 and 2028 than they were in 2026.
‘More than 75% of our output is already committed for 2027, and the majority of discussions with customers today are already around 2028. Overall, the industry demand-supply environment and the outlook is in a very healthy place here.’
Micron and CEO Sanjay Mehotra seem to have delivered not just outstanding Q4 results but also a solidly upbeat FY27 outlook. The issue is, the shares have gained over 270% year-to-date so much of the good news has already been priced in.
If there were any doubts about the strength of AI-driven demand, Mehrotra said a lot of its 2027 high-bandwidth memory chip volume was already sold out. Moreover, prices are ‘much higher’ than 2026, which he said was helping narrow the margin gap between HBM and the rest of the memory business.
Seemingly every question we and other analysts were asking – on demand, pricing, margins and the outlook – has been answered positively. In theory, therefore, we should see upgrades to forecasts. Without them, we suspect the shares will give back some of their outsize gains.