

Shares in engineering group Renishaw (LON:RSW) returned to a five-year high after the firm posted strong FY26 earnings and announced a special dividend. CEO Will Lee said the company had made ‘excellent progress’ and was ‘well positioned in attractive markets with substantial growth opportunities’.
Record profit and a strong start to FY27
For the year to June, Gloucestershire-based Renishaw (LON:RSW) reported revenue of £815.8 million, in line with previous guidance. Adjusted operating profit of £152.9 million and pre-tax profit of £168 million, a new company record, were marginally above guidance.
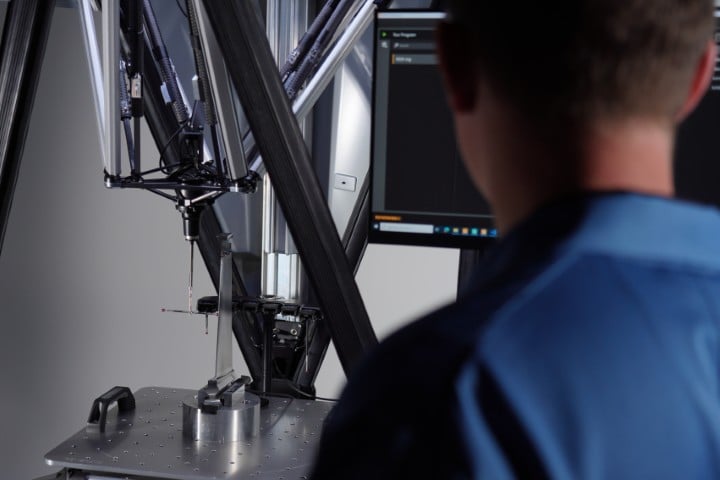
Revenue growth was driven by strong demand from customers in the semiconductor, aerospace and defence sectors. The company noted its new product lines were gaining traction, especially additive manufacturing systems, metrology systems and software.
Renishaw FY26 results
| FY26 | FY25 | Change | |
| Revenue (£m) | 815.8 | 713 | +14% |
| Operating profit (£m) | 152.9 | 112.3 | +36% |
| Pre-tax profit (£m) | 168 | 127.2 | +32% |
| EPS (p) | 179.5 | 137.8 | +30% |
| DPS (p) | 82 | 78.1 | +5% |
Source: Company accounts
The firm’s core business of Industrial Metrology grew its revenue by 4% to £447 million, while Position Measurement revenue climbed 26% to £207 million. The star performer, however, was Specialised Technologies, the smallest business, which increased sales 43% to £107 million.
Demand accelerated during the course of the year, with an exit rate of 28% in the final quarter, double the annual growth rate. The firm also noted average through-the-cycle revenue growth had risen to 8% in the five years since 2021.
CEO Will Lee said the current financial year had ‘started strongly’ thanks to the upturn in demand for semiconductor manufacturing equipment. ‘We expect further strong progress on revenue, profit and operating margin in the year ahead’, added Lee.
Solid balance sheet and a specal dividend
The group ended the year with a strong balance sheet and cash and deposit balances of £291 million, up from £274 million previously. Cash conversion was lower at 79% versus 91% due to higher working capital needs to support record sales and a growing order book.
The firm declared a final dividend of 65.2p per share, bring the annual figure to 82p, a 5% increase on FY25. It also announced a one-off special dividend of 70p per share payable on 3 December to shareholders registered as of 30 October.
We said in our preview Renishaw was a world leader with strong end markets and today’s results reinforce that view. The firm flagged the upturn in demand for semiconductor manufacturing equipment in H1, and it looks pretty durable.
The shares have gained over 60% year-to-date, but that just takes them back to their 2021 level. If through-the-cycle revenue is growing at 8%, and could accelerate thanks to record orders, analysts need to revise their forecasts.
As we also pointed out in our preview, Renishaw is the kind of company foreign buyers and trade rivals would love to buy. Thanks to the foresight of the founding families, however, it looks unlikely the market is going to lose this particular star turn.