

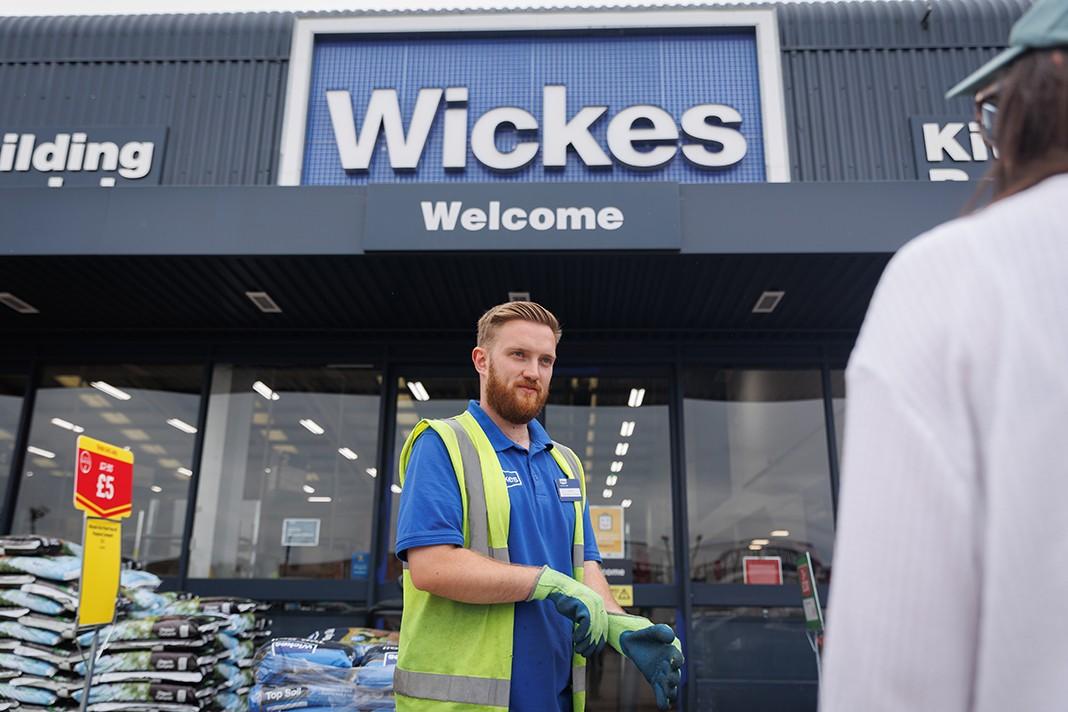
Shares in Wickes (LON:WIX) rallied after the home improvement retailer reported a ‘significantly improved’ trading trend in Q3-to-date. There was also relief as Wickes insisted it is on track to meet FY26 consensus expectations of circa 10% growth in adjusted pre-tax profits.
Led by charismatic CEO David Wood, Wickes is the UK’s second-largest home improvement retailer behind B&Q. The business is segmented into two divisions: Retail (DIY & Trade) and Design and Installation.
Significantly improved trend
Wickes has seen a ‘significantly improved trend’ in Q3 so far, with retail like-for-like sales accelerating to mid-single-digit growth.
| Year to December | FY26E | FY27E | FY28E |
| Revenue (£m) | 1,685.3 | 1,752.7 | 1,833.3 |
| Adjusted pre-tax profit (£m) | 55 | 62.8 | 70.7 |
| EPS (p) | 17.7 | 20.2 | 22.8 |
Source: Investec Equities estimates
Drawing confidence from this momentum, productivity programmes, new store openings and lower business rates, Wickes is confident in delivering FY26 consensus pre-tax profits of £54.6 million.
Resilient H1
H1 results showed a 1.1% rise in pre-tax profits to £27.6 million. Total revenue ticked up 2.1% to £865.3 million.
This resilient performance was delivered despite a wet Q1 and heatwaves in Q2, as revenue growth and productivity actions partially offset cost inflation.
Good progress was made on strategic initiatives, with Wickes delivering 5% growth in TradePro sales and further market share gains.
What did Wood say?
‘Our value-led retail proposition continues to appeal to both DIY and Trade customers, with TradePro achieving record levels of active members,’ said Wood. ‘Design & Installation delivered sales remain in growth, with particularly strong sales of Wickes Bespoke Bathrooms and Lifestyle Kitchens, demonstrating the appeal of our broader offer.’
Wood added: ‘Looking ahead, our digital investments are improving the customer experience and operational efficiencies and we remain confident in our strategy, continuing to invest for growth, including our ambition to reach 300 stores, to drive sustainable long-term value for shareholders.’
Given the difficult UK consumer environment, a tough housing market and the weather extremes seen in H1, these are highly resilient results.
While the near-term outlook is challenging, we think Wickes can continue to outperform competitors over the medium-to-long term while progressing its ambition to reach 300 stores.
In addition, the FTSE 250 retailer has a long runway for growth. It has just 5% of a £35 billion total addressable market of home improvement, kitchens, bathrooms and home energy solutions in the UK.
Jefferies, which has a 250p price target for Wickes, commented: ‘A reassuring update that should be taken well, particularly set against market concerns that FY estimates could need to be trimmed.’
With a 329p price target, Investec said: ‘Wickes is well-positioned to keep outperforming and taking market share, in our view, as it continues to invest in its proven growth levers and new space. It is well-positioned to also take advantage of the cyclical upturn when consumer confidence improves.’
Disclaimer: The author James Crux has a personal interest in Wickes.