

This article explains why Q3 US earnings, which start this week, could jump more than 35% from last year. If they do, it will mark three consecutive quarters of over 25% annual earnings growth for the S&P 500 index.
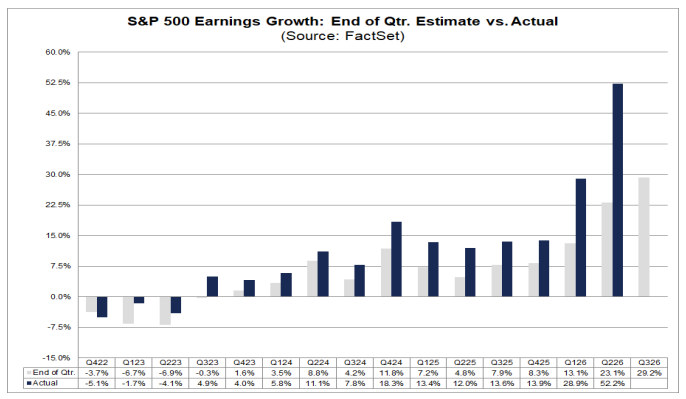
According to FactSet, the consensus for S&P 500 earnings growth at the end of September was 29.2%, up from the June consensus of 26.7%.
Source: FactSet
However, US earnings have beaten forecasts in all but three quarters in the last 10 years. The average earnings growth rate over that period has risen 6.9%, with 77% of companies reporting forecast-beating earnings.
Over five years, the average growth rate has risen 6.4% with 78% of companies beating forecasts. Over one year, the average growth rate has risen a staggering 14.1%, with 82% of companies beating forecasts.
Therefore, the index will likely report earnings growth of more than 35% for Q3 says FactSet senior analyst John Butters. And, depending on which period you choose, earnings growth could be anywhere from 35.6% based on the five-year average up to 43.3% based on the one-year average.
Range of potential Q3 outcomes based on past averages
| Historic ‘beat’ | Current Q3 growth forecast | Potential outcome | |
| Over 10 years | 6.9% | 29.2% | 36.1% |
| Over five years | 6.4% | 29.2% | 35.6% |
| Over one year | 14.1% | 29.2% | 43.3% |
Source: FactSet, Sharesify
Positive guidance hits a new record
As of 2 October, 72 companies had issued positive earnings guidance for Q3. That compared with 44% companies issuing negative earnings guidance. At the same time, 14 companies had already reported a positive earnings surprise with 12 companies reporting a positive revenue surprise.
The number of companies issuing positive Q3 EPS guidance was well above the five-year average of 42 and the 10-year average of 40. In fact, Q3 marks the highest number of companies issuing positive earnings guidance since FactSet began tracking this metric in 2006. The previous record was 65, which was in Q2 2021.
In contrast, the number of companies issuing negative EPS guidance was below the five-year average of 62 and the 10-year average of 57. So far, Q3 marks the lowest number of S&P 500 companies issuing negative earnings guidance since Q3 2021, which was 39.
Which sectors are issuing positive guidance?
Out of 11 sectors, Information Technology has the highest incidence of positive EPS guidance with 44 companies. This is well above both the five-year average of 24 and the 10-year average of 20 for the sector.
It also ties with Q2 2026 for the highest number of technology companies issuing positive quarterly guidance since FactSet started tracking this metric in 2006.
At the industry level, Software and Semiconductors & Semiconductor Equipment have the highest number of companies issuing positive guidance at 12 and 11 respectively.
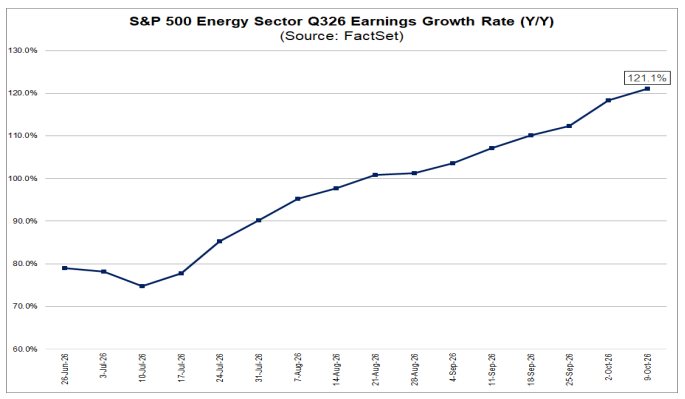
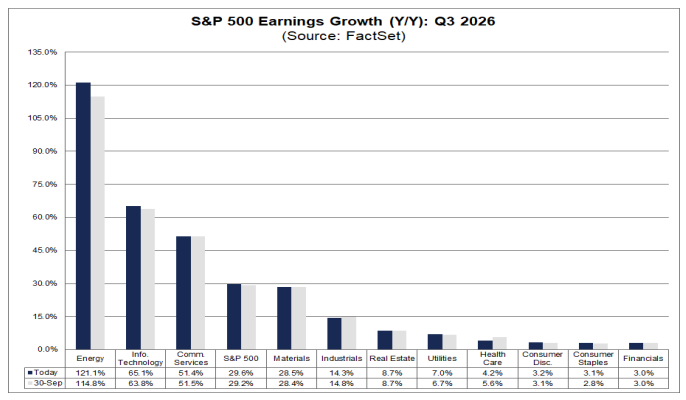
It’s also worth noting Information Technology is expected to report the second-highest earnings growth rate of all sectors at 65%. The Energy sector is seen posting the highest earnings growth rate at 121%, up from a forecast of 79% in June.
Source: FactSet
Between 30 June and 30 September, the WTI oil price rose 30% to $90.42 and averaged $85.68 or 32% more than in Q3 2025. Refining & Marketing earnings are seen soaring 462%, while Integrated Oil & Gas earnings are seen rising 113%.
The tailwind from higher energy prices and higher refined product prices is expected to last into next year. Analysts are forecasting 117% earnings growth for Q2 2026 and 87% growth for Q1 2027.
All 11 sectors in the S&P500 are expected to report earning growth in Q3. Five are expected to report double-digit growth or more: Energy, Information Technology, Communication Services, Materials and Industrials.
Source: FactSet
