

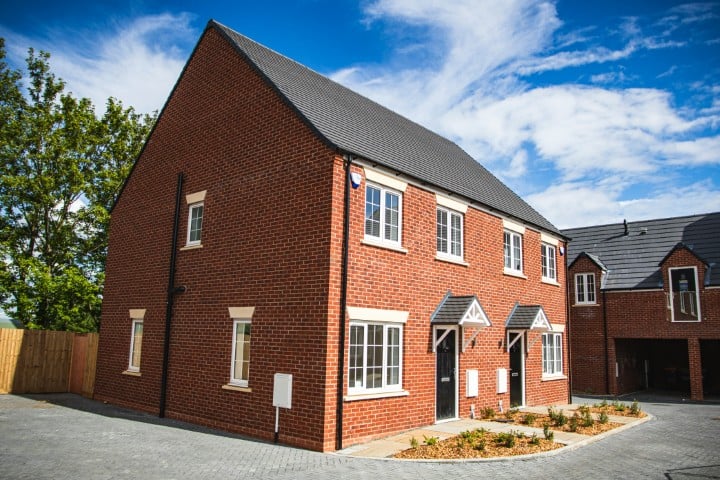
Housebuilder Barratt Redrow (LON:BTRW) maintained its FY27 outlook despite 12% fewer completions in the four months to October. The firm said trading had been ‘resilient against a backdrop of challenging market conditions, with continued pressure on affordability’.
FY outlook maintained
For the four months to October, Barratt reported a 12% drop in completions to 3,223 against 3,665 a year ago. However, the forward order book rose 4% to 11,086 homes, with a value of £3.31 billion against £3.28 billion previously.
Meanwhile, the group was 56% forward-sold for FY27 private home completions with 62% either completed or exchanged. Also, weekly reservations per outlet were 0.59 against 0.57 last year, including the private rental sector, or 243 units per week against 228 units.
The firm maintained its current-year guidance despite the ‘challenging’ market backdrop and pressure on affordability for potential homebuyers. While it welcomed the ‘Your First Home’ scheme, it said it was is too early to assess its impact on first-time buyer activity.
What did the CEO say?
New CEO Dean Banks, who succeeded David Thomas in mid-September, said there was ‘much to build on’ at the group. While welcoming the new homes initiative, Banks stressed planning reform was also needed to support increased housing delivery.
Barratt reduced its target for completions back in September, so today’s update is consistent with its most recent guidance. The firm will remain ‘focused on driving cost efficiencies, disciplined land investment and tightly managed control of work in progress’, added Banks.
There’s no denying the mood music in the housebuilding sector is improving, albeit gradually. Both Barratt Redrow and Bellway (LON:BWY) have maintained their outlooks despite a tough backdrop and financially-constrained buyers.
However, investors have tried to call the bottom so many times, only to be disappointed. Therefore we aren’t surprised by today’s lukewarm response. Barratt shares have been in a clear downtrend since 2021, and it will take a big positive surprise for them to break out.
For value investors, though, the stock should be looking interesting. According to Stockopedia, the shares trade on 0.56 times book value, added to which Barratt has a large cash pile. Meanwhile, based on our CAPE model the stock trades on less than 10 times cyclically-adjusted earnings or one standard deviation below the 30-year mean.
