

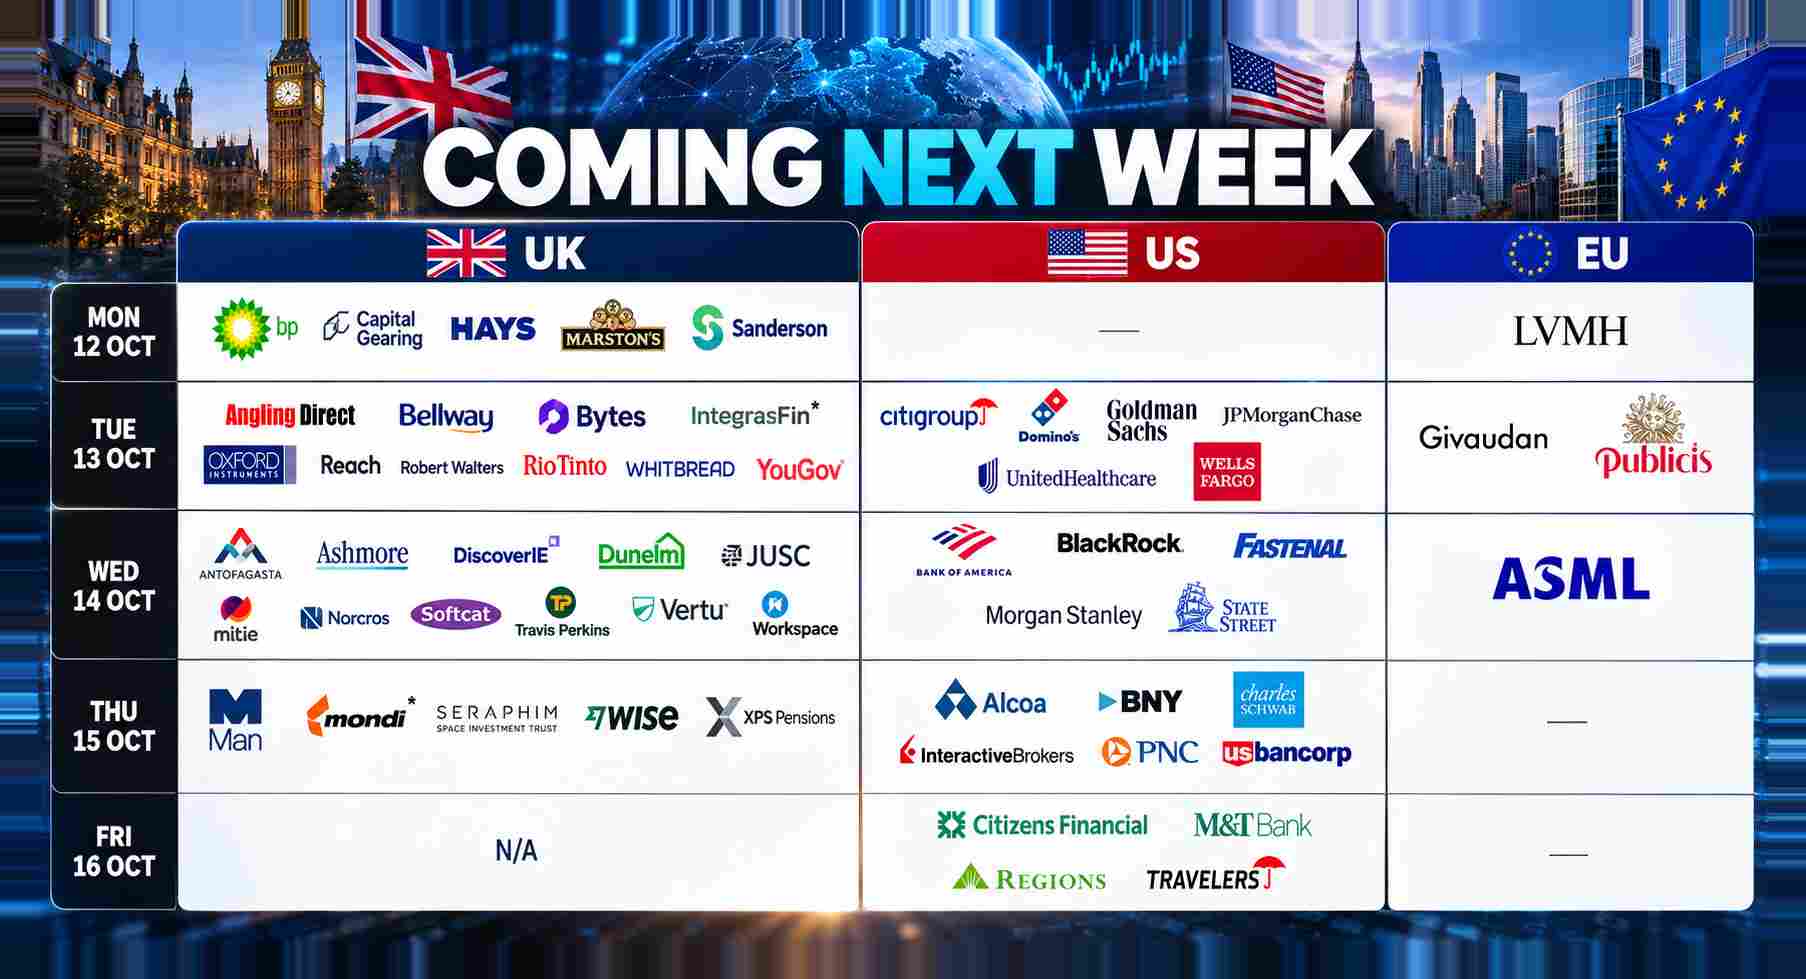
UK retail investors face a busy week of corporate updates from 12–16 October, with technology, mining, banking and consumer spending among the key themes to watch. Bytes Technology and Softcat headline Tuesday and Wednesday’s UK technology earnings, offering fresh insight into corporate IT spending, cloud adoption and demand for AI infrastructure. Investors will also scrutinise Rio Tinto and Antofagasta for signals on commodity demand, Chinese economic activity and the outlook for metals, while Bellway, Whitbread and Dunelm provide perspectives on housing, travel and household spending.
Thursday brings updates from Wise and Man Group, putting international payments, asset management and investor activity in focus. BP kicks off the week, with energy markets and shareholder returns likely to feature prominently.
Across Europe, luxury giant LVMH reports on Monday, followed by Givaudan and Publicis on Tuesday. Semiconductor heavyweight ASML is Wednesday’s major European highlight, with investors watching its order book and outlook for signs of sustained AI-driven chipmaking investment.
With US earnings season also gathering pace, results from major American banks and financial institutions will help shape sentiment towards global equities.
JPMorgan Chase (NYSE:JPM)
With a market cap of $875 billion and annual revenue of over $200 billion, JPMorgan Chase (NYSE:JPM) will set the tone for Q3 earnings when it reports on Tuesday 13 October. Analysts are currently expecting a 17% increase in EPS to $5.94 and a 12.5% increase in revenue to $52.2 billion.
Chairman and CEO Jamie Dimon is reasonably sanguine on the health of US companies and the US consumer. However, he has been doing the rounds ahead of the results warning of the dangers of inflation and rising global deficits.
‘There’s a risk inflation is sticky and rates continue to go up’, says Dimon, which will impact companies needing to borrow money. Therefore, finance teams need to be prepared for higher interest rates, whether or not they happen.
Consensus estimates for JPMorgan Chase
| Q3 2026 | FY 2026 | FY 2027 | |
| Revenue (bn) | $52.2 | $208.9 | $214.0 |
| EPS | $5.94 | $24.16 | $25.23 |
Source: Zacks, Stockopedia
Dimon also warned rising deficits could force up interest rates as investors demand a higher ‘risk premium’ to lend money to governments. That in turn could feed into corporate debt and credit spreads, creating more headwinds for companies.
The key, says Dimon, is not to be complacent and to tackle the issue before it becomes a crisis. ‘If it becomes a crisis, we will deal with it, just in a much less pleasant way’, he adds.
Dunelm (LON:DNLM)
Homewares leader Dunelm (LON:DNLM) has been in the doghouse with investors since 8 September, when the curtains-to-kitchenware retailer downgraded FY27 profit guidance.
The Leicester-headquartered company warned heatwaves had caused ‘significantly softer’ trading in the first six weeks of FY27, although sales had picked up in more recent weeks.
Dunelm continued to face challenging market conditions during the remainder of the first quarter, as balmy temperatures persisted through July, August and September. And given tough homewares competition, increased costs and a squeezed consumer, we think there is potential for another downgrade with Dunelm’s Q1 update (15 Oct).
Consensus estimates for Dunelm
| FY 2027 | FY 2028 | FY 2029 | |
| Revenue (m) | £1,897 | £1,982 | £2,092 |
| Adjusted pre-tax profit (m) | £211 | £221 | £234 |
| EPS | 77p | 81p | 85p |
Source: Dunelm-compiled consensus
But if the Leicester-based firm can maintain FY27 guidance and report further market share gains for Q1, investors might just cosy up to the stock again. On results day, analysts will want to hear more about CEO Clo Moriarty’s bold three-year growth plan to ‘win hearts and homes’.
This self-funding strategy aims to accelerate revenue growth back to mid-to-high single-digit levels. It will be supported by around £100 million of cost savings and accelerated investment in stores and digital channels. Consensus estimates for FY27 point to flat adjusted pre-tax profits of £211 million, rising to £221 million and £234 million in FY28 and FY29 respectively.
Bytes technology (LON:BYIT) / Softcat (LON:SCT)
Investors will focus on earnings momentum, profit margins and the outlook for AI-driven IT spending when Bytes Technology (LON:BYIT) reports half-year results on Tuesday 13 October and Softcat (LON:SCT) publishes full-year results on Wednesday 14 October.
Bytes has already upgraded FY2027 guidance after a strong first half, forecasting gross profit growth in the low-to-mid teens and operating profit growth in the low-to-mid single digits. Gross profit rose approximately 18% and operating profit 6% in the first half, making evidence of improving margins and stronger cash conversion key share-price catalysts. Investors will also want to see whether demand for cloud computing, cybersecurity and AI software can sustain this momentum.
Consensus estimates for Bytes Technology
| Bytes Technology | FY 2026 (reported) | FY 2027 | FY 2028 |
| Revenue (m) | £221 | £247 | £269 |
| EPS | 20.7p | 22.41p | 24.5p |
Source: Stockopedia
Consensus estimates for Softcat
| Softcat | FY 2027 (reported) | FY 2028 | FY 2029 |
| Revenue (m) | £1,458 | £1,803 | £2,050 |
| EPS | 76.5p | 81.3p | 86.1p |
Source: Stockopedia
Softcat’s results will be judged against its upgraded FY2026 outlook for high-teens underlying operating profit growth. Investors will scrutinise gross profit, customer demand and cash generation, alongside guidance for FY2027. Its planned £785m acquisition of US IT solutions provider GDT adds another major consideration: the potential to expand in AI infrastructure, networking and cybersecurity must justify the financial risks and integration costs.
Both shares could rise if results exceed expectations, but guidance, margins and the quality of future growth will matter more than headline revenue alone.
You might also like:
