

Fast food firm Domino’s Pizza (LON:DOM) stuck to its FY26 earnings targets despite a slowdown in Q3 sales growth. CEO Nicola Frampton admitted there was ‘work to be done’, but was confident the company would achieve its full-year expectations.
Positive growth despite slowdown
For the three months to September, Domino’s posted growth across all metrics, continuing the positive momentum delivered in H1. Total system sales increased by 3.5%, with LFL growth of 2.3%, while orders rose by 2.6% or 1.4% on a LFL basis.
Sales growth was slower than in Q2, which saw a greater benefit from the World Cup, but all three months were positive. Order growth was in line with H1 on a LFL basis but behind Q2.
Domino’s Pizza 2026 quarterly LFL performance
| Q1 | Q2 | H1 | Q3 | YTD | |
| Sales | 4.5% | 5.2% | 4.9% | 2.3% | 4.0% |
| Orders | 0.9% | 2.2% | 1.6% | 1.4% | 1.5% |
Source: Company accounts
Innovation supporting growth
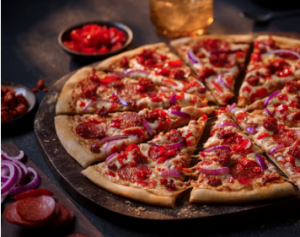
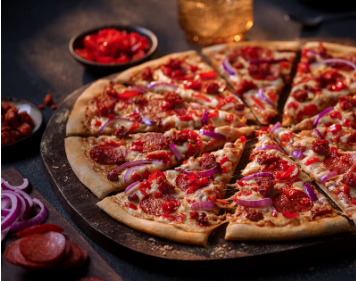
The firm said growth in both pizza and its new CHICK ‘N’ DIP offering helped drive Q3 sales. The Italianos pizza range remained popular, and customer feedback and advocacy levels for CHICK ‘N’ DIP were ‘strong’.
‘Our performance year-to-date reflects our organic growth strategy and we have been rewarded by our focus on the core Domino’s business model’, said the CEO. ‘The proof points of our innovation in Italianos and CHICK ‘N’ DIP, combined with our fantastic brand, quality franchisee partners and leading supply chain have enabled us to attract more customers.’
With all its major cost categories fixed for this year and into next year, Domino’s has good visibility over input prices. Combined with its growth strategy, that gives it confidence in delivering earnings in line with market expectations.
Domino’s has been phenomenally successful in terms of sales and earnings growth over the last 25 years. Over that time the company has increased its EPS by an average of 17% per year, including during Covid when traditional restaurants were closed.
Sadly, shareholders haven’t seen much benefit as the shares have de-rated tremendously over the last decade. Today they are trading close to their lowest valuation since coming to market.
Yet, as more people dine in instead of dining out, Domino’s is perfectly placed to pick up customers, especially with rivals closing stores. And with costs fixed across all categories into next year it has control over its biggest expense.
Regarding the menu, by focusing on its core range and offering more traditional pizzas like thinner-crust Italianos, it has stepped things up a notch. Similarly, by adding a chicken range it has hugely increased its addressable market and order sizes should grow.
The share price has perked up somewhat this year, and we wouldn’t be worried about today’s pullback. In retrospect, it may prove to have been a good buying opportunity given how undervalued the stock looks.
