

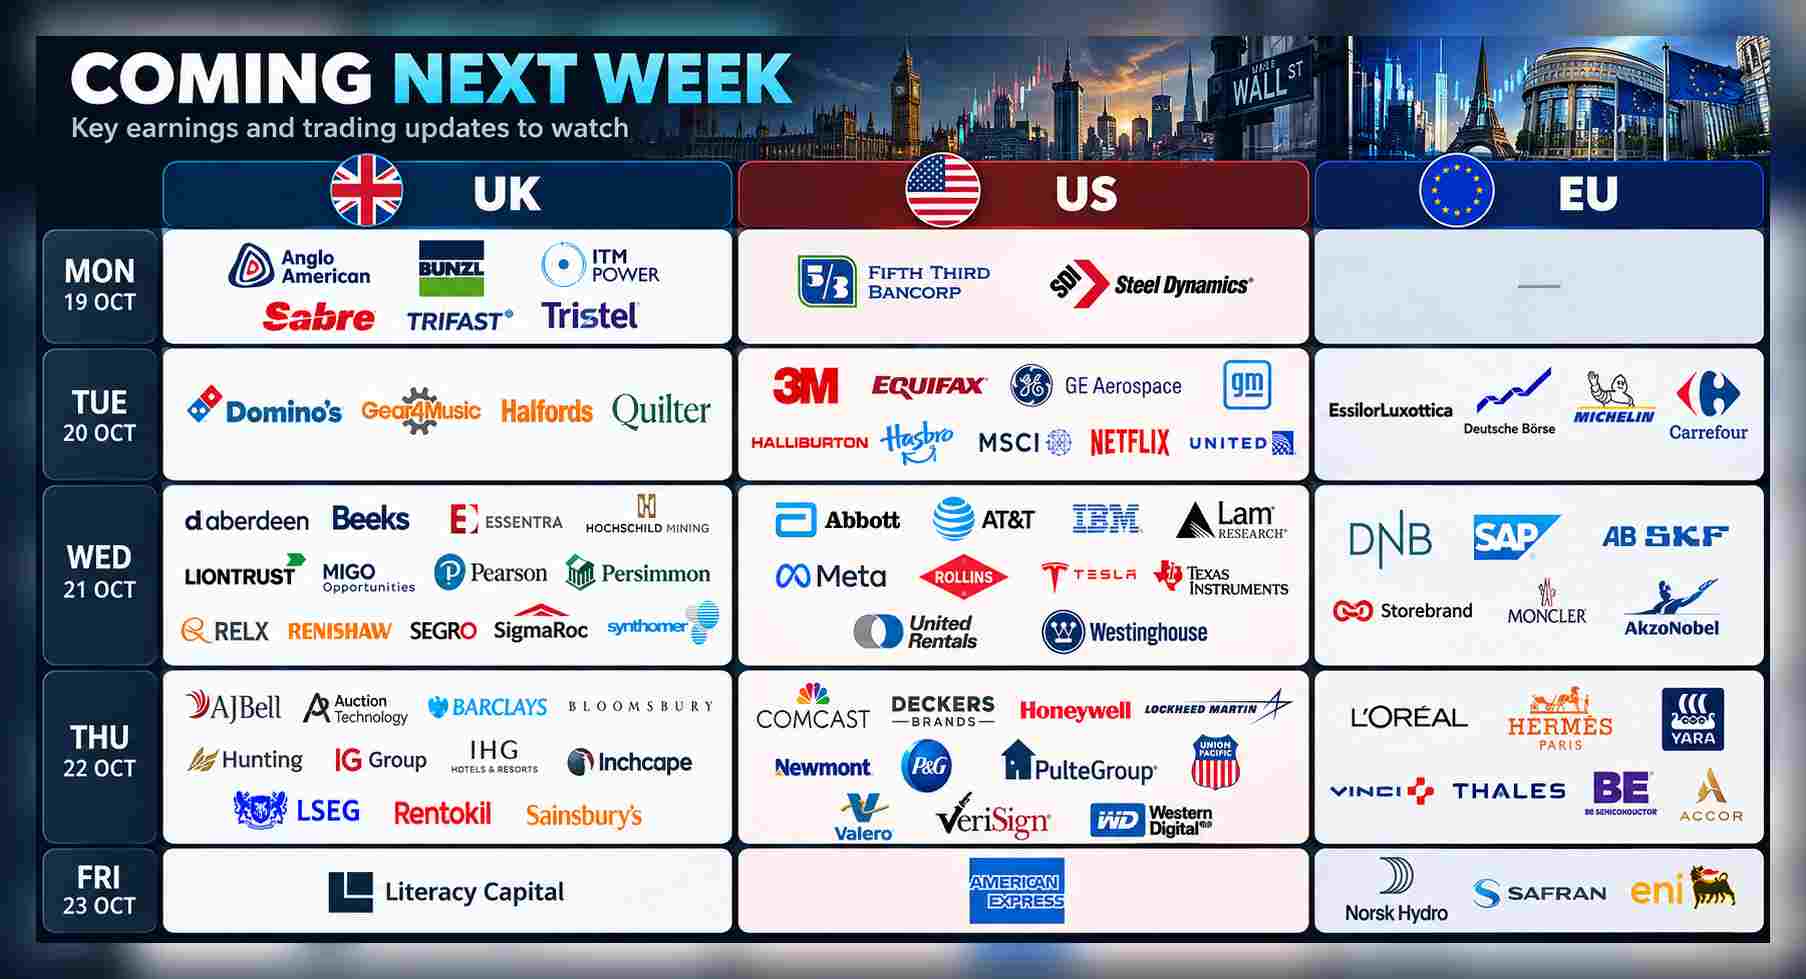
Next week’s earnings calendar offers plenty for UK retail investors to watch, with Netflix, Tesla, Meta Platforms and SAP among the biggest global names reporting. In the UK, Anglo American, RELX, Pearson, Persimmon, Barclays, AJ Bell, Sainsbury and LSE Group should attract particular attention, offering a broad read on commodities, advertising and information services, housing, banking, retail and investment platforms. Domino’s, Halfords and Quilter also provide useful insight into UK consumer spending and wealth management.
Why US earnings growth could top 35% this quarter
For investors following the AI trade, Wednesday could be especially important, with Meta, Tesla, IBM, Lam Research and Texas Instruments reporting in the US, while SAP reports in Europe. Semiconductor investors will also be watching BE Semiconductor and Western Digital. Elsewhere, L’Oréal, Hermès and IHG offer clues on global consumer demand and travel, while GE Aerospace, Honeywell and Safran provide an update on industrial and aerospace activity. With such a concentrated line-up, the week could provide fresh evidence on whether earnings growth is keeping pace with elevated market expectations.
Procter & Gamble (NYSE:PG)
Investors will be praying for organic sales growth acceleration when consumer goods goliath Procter & Gamble (NYSE:PG) announces Q1 earnings on 22 October. Led by CEO Shailesh Jejurikar, the Pampers-to-Pantene maker will need to report progress with cost savings, and raise FY27 guidance, for the stock to rally on results day.
The Cincinnati-based group’s brands, which include Head & Shoulders, Gillette, Tide and Oral-B, are trusted in millions of kitchens, laundry rooms and bathrooms. However, cash-strapped consumers continue to grapple with inflationary pressures. And in recent years, they have gravitated to cheaper competing brands, which has dragged on Procter & Gamble’s growth.
Procter & Gamble consensus forecasts
| Year to June | FY26A | FY27E | FY28E |
| Revenue ($m) | 87,032 | 88,802 | 91,252 |
| Net profit ($m) | 16,046 | 16,774 | 17,567 |
| EPS ($) | 6.91 | 6.98 | 7.39 |
| DPS ($) | 4.26 | 4.40 | 4.60 |
Source: Stockopedia
For decades, investors paid a premium for the predictability of Procter & Gamble’s earnings, but organic sales were flat in Q4. And the US company is wrestling with elevated costs too.
On 29 July, Procter & Gamble reported EPS (earnings per share) of $1.43 for Q4, topping the $1.41 Wall Street had called for, although the 2% rise in revenue to $21.20 billion was shy of the $21.38 billion consensus estimate. For Q1, analysts expect Procter & Gamble to report earnings of $1.88 on revenue of $22.77 billion. For FY27, management guided for EPS in the $6.89 to $7.11 range.
Despite facing short-term challenges, the dependability of Procter & Gamble’s earnings and cash flows is reflected in the fact the company has paid a dividend for 136 years. The company also has an impressive 70 years of unbroken dividend growth under its belt.
SAP (ETR:SAP)
For UK retail investors, SAP’s (ETR:SAP) Q3 results on Wednesday 21 October will be a key test of whether the German software giant can maintain its rapid shift towards cloud and AI. The headline number to watch is current cloud backlog, which reached €22.9bn in Q2, up 26% at constant currencies. SAP has warned that backlog growth will slightly decelerate, so a result materially above or below expectations could drive a sharp share price reaction.
Cloud revenue is expected to rise around 24% YoY to €6.58bn, while investors will scrutinise operating margins, with consensus at 29%.
SAP consensus forecasts
| Q3 2025 | Q3 2026 | YoY Growth | FY 20226 | |
| Revenue (bn) | €9.08 | €10.12 | 11% | €40.32 |
| EPS | €1.59 | €1.80 | 13% | €7.06 |
Source: SAP-compiled consensus
The bigger question is whether AI products and SAP’s ‘Autonomous Enterprise’ strategy are translating into stronger customer demand and contracts. Management’s comments on 2027 growth, AI monetisation and margins could therefore matter more than the quarter itself.
SAP is also maintaining 2026 cloud revenue guidance of €25.8bn–€26.2bn, making any upgrade potentially significant for sentiment across European software stocks.
Domino’s Pizza (LON:DOM)
Shares in Domino’s Pizza (LON:DOM) are down almost 40% on a five-year view, but the stock has rallied since March and is up more than 20% over the past year. Investors are anticipating a few slices of positive news when the pizza brand delivers its Q3 trading update on 21 October.
Sharesify expects the FTSE 250 firm to highlight progress with new store openings as well as further UK takeaway pizza market share gains. Investors can also expect confirmation of a strong consumer response to its Chick ‘N’ Dip range. Rather than eating into existing pizza sales, Chick ‘N’ Dip is helping the group to attract new chicken customers.
Domino’s Pizza consensus forecasts
| Year to December | FY25A | FY26E | FY27E |
| Revenue (£m) | 685 | 712 | 734 |
| Net profit (£m) | 58.6 | 68.4 | 71.2 |
| EPS (p) | 18.2 | 17.6 | 18.5 |
| DPS (p) | 11.3 | 11.6 | 12.1 |
Source: Stockopedia
Domino’s value offering leaves it well-placed to capture demand from cash-strapped consumers trading down or eating at home more frequently. And the company has grown its UK pizza market share to 53.8% as competitors including Pizza Hut UK and Franco Manca shutter locations.
Back in August, Domino’s served up encouraging H1 results and a positive outlook statement. The company reported like-for-like sales up 4.9% and 1.6% growth in orders for the half ended 28 June, driven by growth in both pizza and Chick ‘N’ Dip, as well as a World Cup boost.
‘We have carried positive momentum into July and, with our major cost lines hedged through 2026 and into next year, remain confident in delivering our full-year expectations,’ said CEO Nicola Frampton. For FY26, consensus calls for a rise in sales from £685 million to £712 million, ahead of £734 million revenues in FY27. Cash-generative Domino’s is forecast to raise the dividend from 11.3p to 11.6p, ahead of an increase to 12.1p in FY27.
You might also like:
