

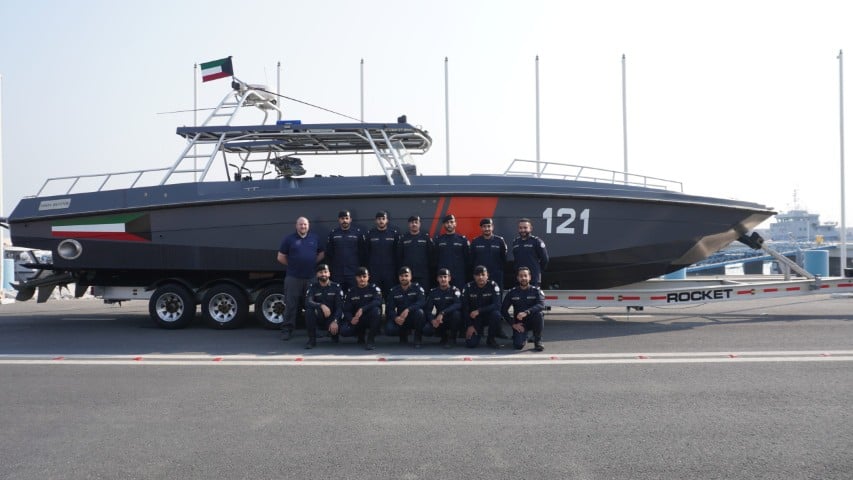
AIM-listed civil defence and security firm SRT Marine Systems (LON:SRT) posted a six-fold increase in annual profit. The group also revealed its validated pipeline of sales opportunities had expanded from £1.8 billion to £2.4 billion.
Six-fold increase in profit
For the year to June 2026, the Radstock-based firm reported a 46% increase in revenue to £114.1 million, in line with forecasts. Meanwhile, net profit increased 653% from £1.4 million to £10.7 million, ahead of the consensus.
The group also increased net cash generation from £1 million to £37.7 million during the year. As of 30 June, the cash balance was £57.1 million, equivalent to 30% of its market cap.
The company’s total contracted order book expanded by £218.4 million to £539.5 million, while sovereign customers increased from five to six. At the same time, the validated pipeline of sales opportunities increased from £1.8 billion to £2.4 billion.
CEO Simon Tucker said the results showed ‘how rapidly we are developing and growing as a global leader in sovereign civil defence systems’. Having converted 12% of its £1.8 billion sales pipeline, it now has £2.4bn of opportunities and Tucker expects conversion to continue ‘at pace’.
SRT Marine Systems FY26 results (all £ millions)
| FY26 | FY25 | Change | |
| Revenue | 114.1 | 78.0 | +46% |
| Net Profit | 10.7 | 1.4 | +653% |
| Net Cash | 57.1 | 9.9 | +477% |
| Pipeline | 2,400 | 1,800 | +33% |
Source: Company accounts
Technology roll-out
Over the last year, SRT has accelerated the development of its systems technology to meet new threats. Whereas it was previously focused on MDA (marine domain awareness), it has broadened and deepened its command and control capabilities across sea, land and air borders and territories.
This has resulted in rapid growth in interest and opportunities, swelling the pipeline of contract discussions by a third. Existing and new customers want to expand their surveillance capabilities to their land and low-altitude air borders.
SRT has responded by developing anew five-year strategic plan to manage this increased demand. This will drive the business forward ‘to very significantly and rapidly grow revenues and profitability over a three-to-five-year period’, says chair Kevin Finn.
We have championed SRT for some time as it occupies a unique space in the defence and security sector. Its marine surveillance technology is already trusted by half a dozen sovereign states, and it looks to be on the verge of major growth.
Orders tend to be lumpy, however, and the infrastructure build-out ahead of the deployment of its technology is costly. The firm has already said it will make a loss in H1 to December due a heavy weighting of low-margin infrastructure completions, but this will be balanced by higher-margin systems deliverables in H2.
Considering the firm’s FY26 performance and progress, we’re surprised the shares haven’t bounced harder. However, that presents an opportunity for new and existing investors to get on board at an attractive level.
