

Shares in The Works (LON:WRKS) hit a five-year high after the toys, games and books retailer raised FY27 guidance once again and said it carries ‘strong trading momentum’ into the Christmas period.
The latest upgrade reflects the delivery of strong like-for-like sales growth for the half ended 1 November, as CEO Gavin Peck’s strategy continued to deliver.
Upgrade cycle continues
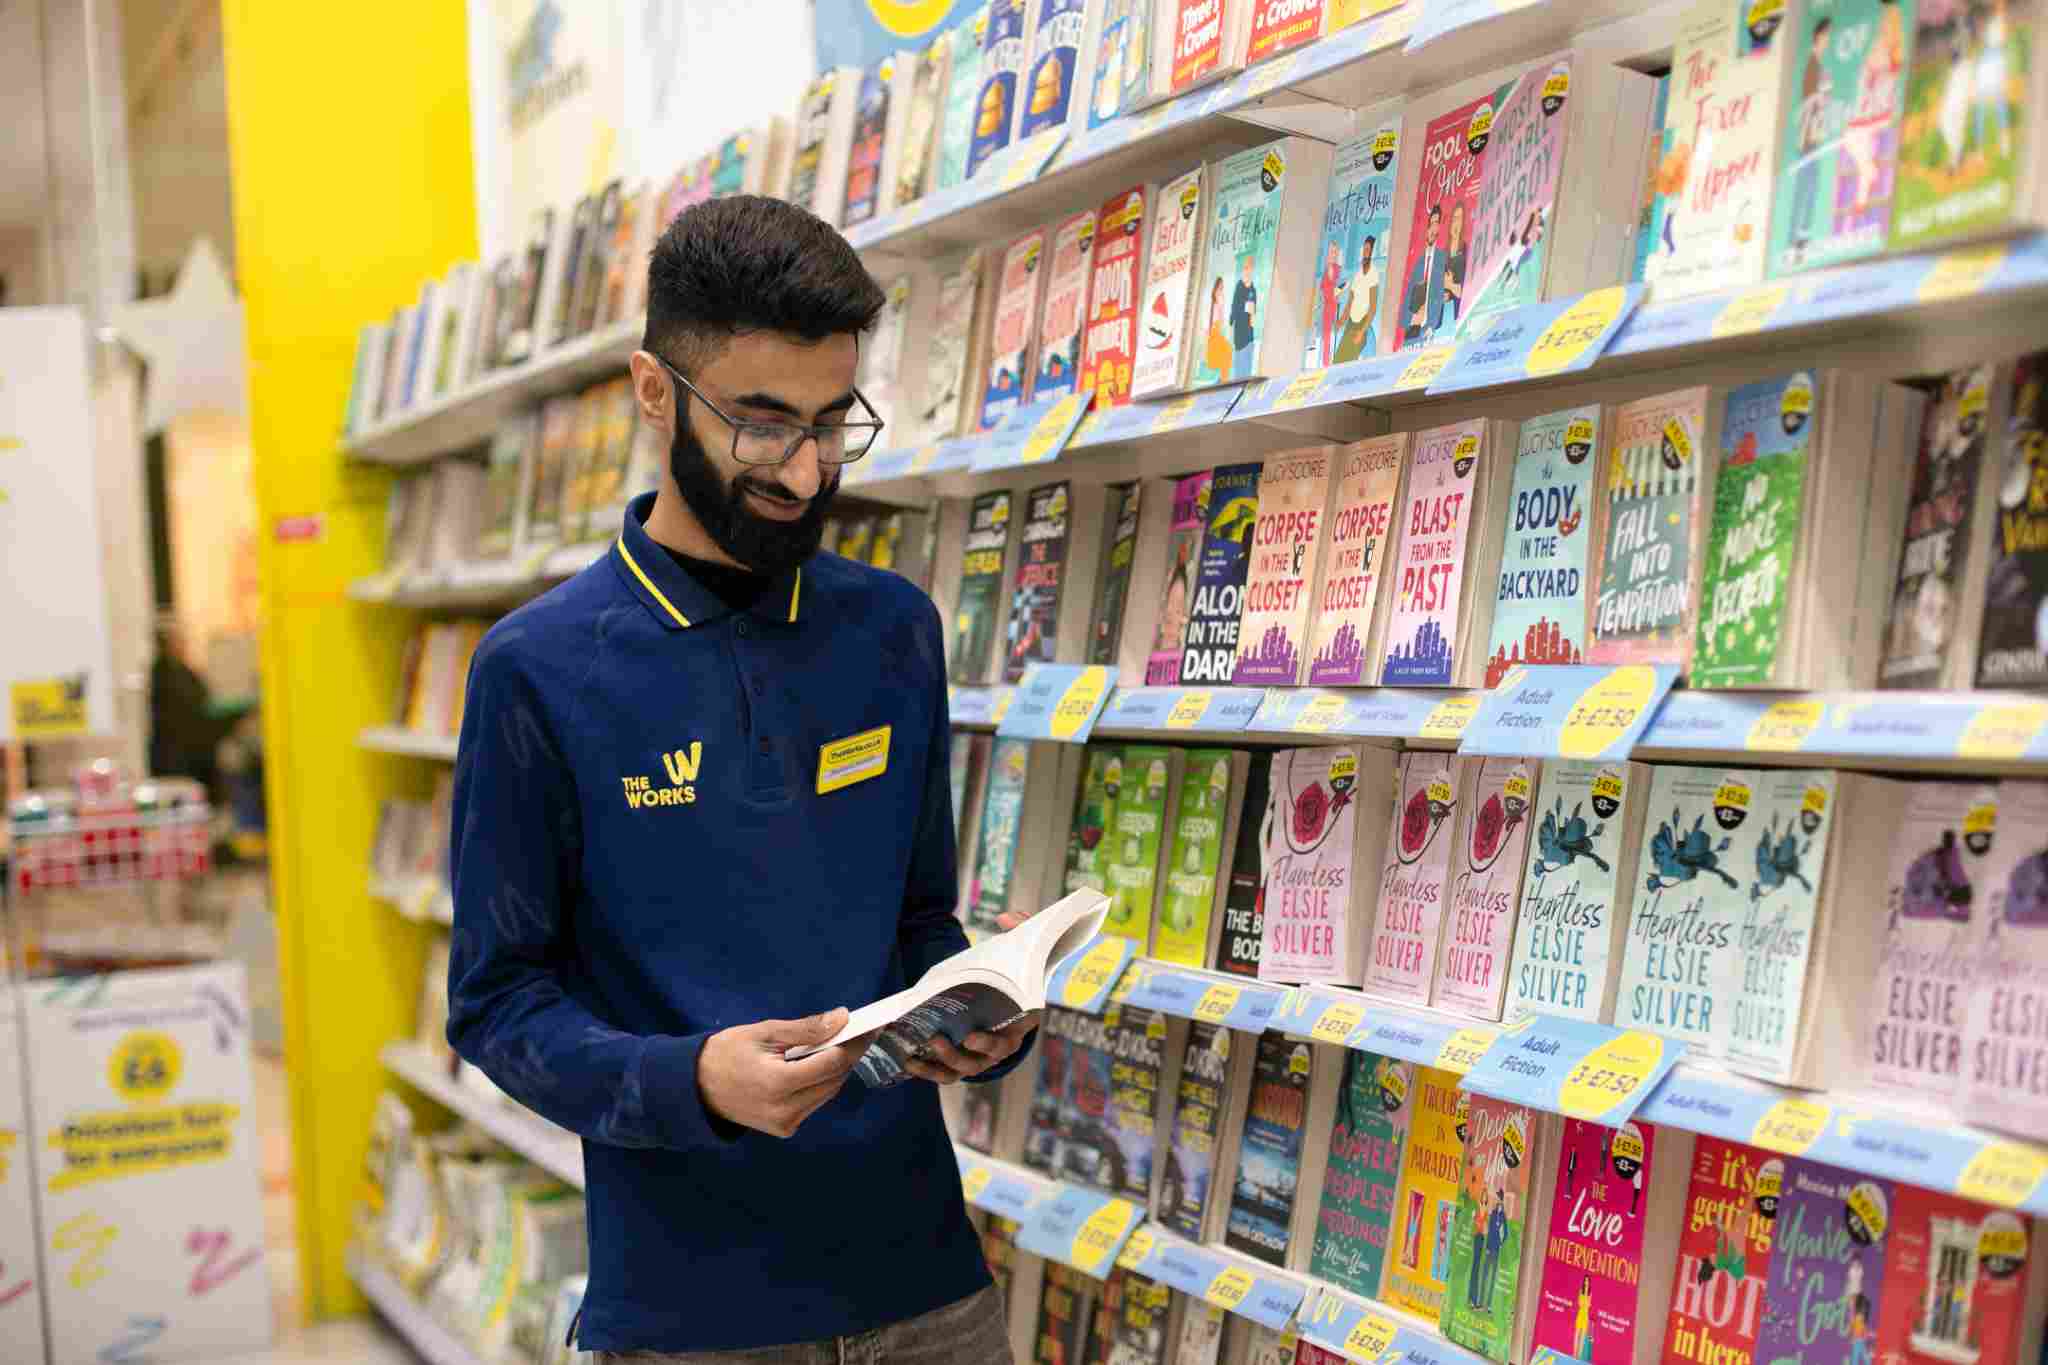
The cut-price arts and crafts purveyor delivered a strong performance in H1 FY27, with effective execution of Peck’s ‘Elevating The Works’ growth strategy driving increased customer demand for its assortment of screen-free products.
Total sales increased by 10.1% to £128.8 million in H1. And like-for-like sales grew 9.8% as The Works outperformed a declining wider non-food market. Peck told Sharesify that growth remained broad-based across all four key product categories, from kids’ pocket money toys to adult fiction books.
‘This outperformance underlines the relevance and appeal of its differentiated screen-free focused value proposition as well as successful execution of its Elevating The Works strategy, which is driving improvements across the business,’ observed Singer Capital Markets’ Matthew McEachran.
Comfortably ahead of consensus
The Works now expects FY27 adjusted EBITDA to be ‘at least £17 million’, comfortably ahead of the previously-guided £16 million. This upwards revision, together with the upgrade announced in early September, represents an increase in FY27 adjusted EBITDA of more than 13% since the start of the financial year.
‘We are delighted to report a strong H1 performance with like for like sales growth of 9.8%, driven by strong customer demand across all our key categories,’ commented Peck. ‘We also delivered strong performances during the Back to School and Halloween trading periods.’
Peck added: ‘We are well positioned as we enter the key Christmas trading period and focussed on giving our customers more inspiration and choice for enjoying Time Well Spent together this Christmas.’
Back in September, we highlighted the potential for further upgrades from The Works, and the company hasn’t let us down. Despite the squeeze on consumer discretionary spending, the retailer’s focus on screen-free products and sharp value credentials give it a golden opportunity to grab market share this Christmas.
Forecasts for The Works
| Year to April | FY26A | FY27E | FY28E |
| Revenue (£m) | 260 | 276.5 | 289.6 |
| Adjusted EBITDA (£m) | 14.1 | 17 | 18 |
| EPS (p) | 8.9 | 11.9 | 13.2 |
Source: The Works, Singer Capital Markets
Peck and his team have rebuilt profitability. And The Works has strong growth potential from new store openings, new product introductions and market share gains at the expense of struggling competitors.
Following today’s update, Singer Capital Markets reiterated its ‘buy’ rating on The Works and flagged scope for yet more upgrades. The broker increased its target price by 5% to 134p and sees ‘a clear roadmap to at least 180p’.
