

Transport technology firm Tracsis (LON:TRCS) has completed its transformation while delivering an improved financial performance in FY26. The reshaped business represents a strong platform for growth and has started FY27 on a confident note.
Transformation complete
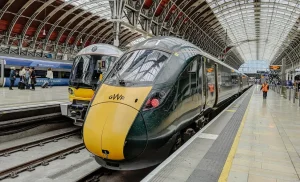
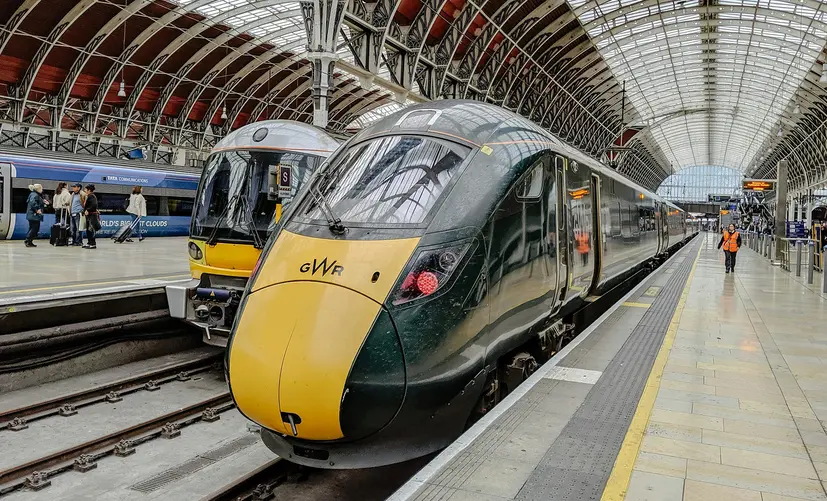
The year to July 2026 was a transformative one for software and services firm Tracsis. Having sold the events division and acquired a German rail technology business, the firm now comprises two divisions with a single operating structure.
Rail Technology & Services represents 70% of revenue, while Data, Analytics & Consultancy represents 30% of revenue. Recurring revenue accounts for 45% of the total against 27% previously, while EBITDA margins have risen to 20% against 15.8%.
‘We are now better equipped to grow in the markets we know best’, commented CEO David Frost. ‘Our broader software portfolio strengthens our position in UK rail, where we have long-standing customer relationships and considerable scope to support more of their operations as the industry evolves.’
Several growth engines
As well as doubling down on UK Rail opportunities, the firm is expanding selectively in North America, Germany and Ireland where it has established positions. With strategic contracts moving into live operation, the work undertaken during the year is expected to support growth in recurring and transactional revenues in FY27.
In August, Tracsis acquired Mistral Data, a high-margin software business with a high level of recurring revenue. The acquisition strengthens the group’s position in the UK rail technology market and accelerates its strategy to develop a scalable software product business.
In Data, Analytics & Consultancy, the firm won a contract with the UK government for its GeoIntelligence business. The contract is due to go live shortly and will generate recurring support and maintenance licence revenue starting this year.
Not having looked into Tracsis in the past, we were impressed by the breadth and depth of the firm’s products and services. We also hadn’t appreciated how embedded the business is in the UK rail industry, along with the opportunities to grow overseas.
Management deserves praise for reshaping the business this year, which can’t have been easy. By selling the events business and buying Mistral, the group has become much more focused.
That makes it a more attractive partner to customers both in the UK and overseas. It also means it has a much higher proportion of recurring revenue and significantly higher margins.
