

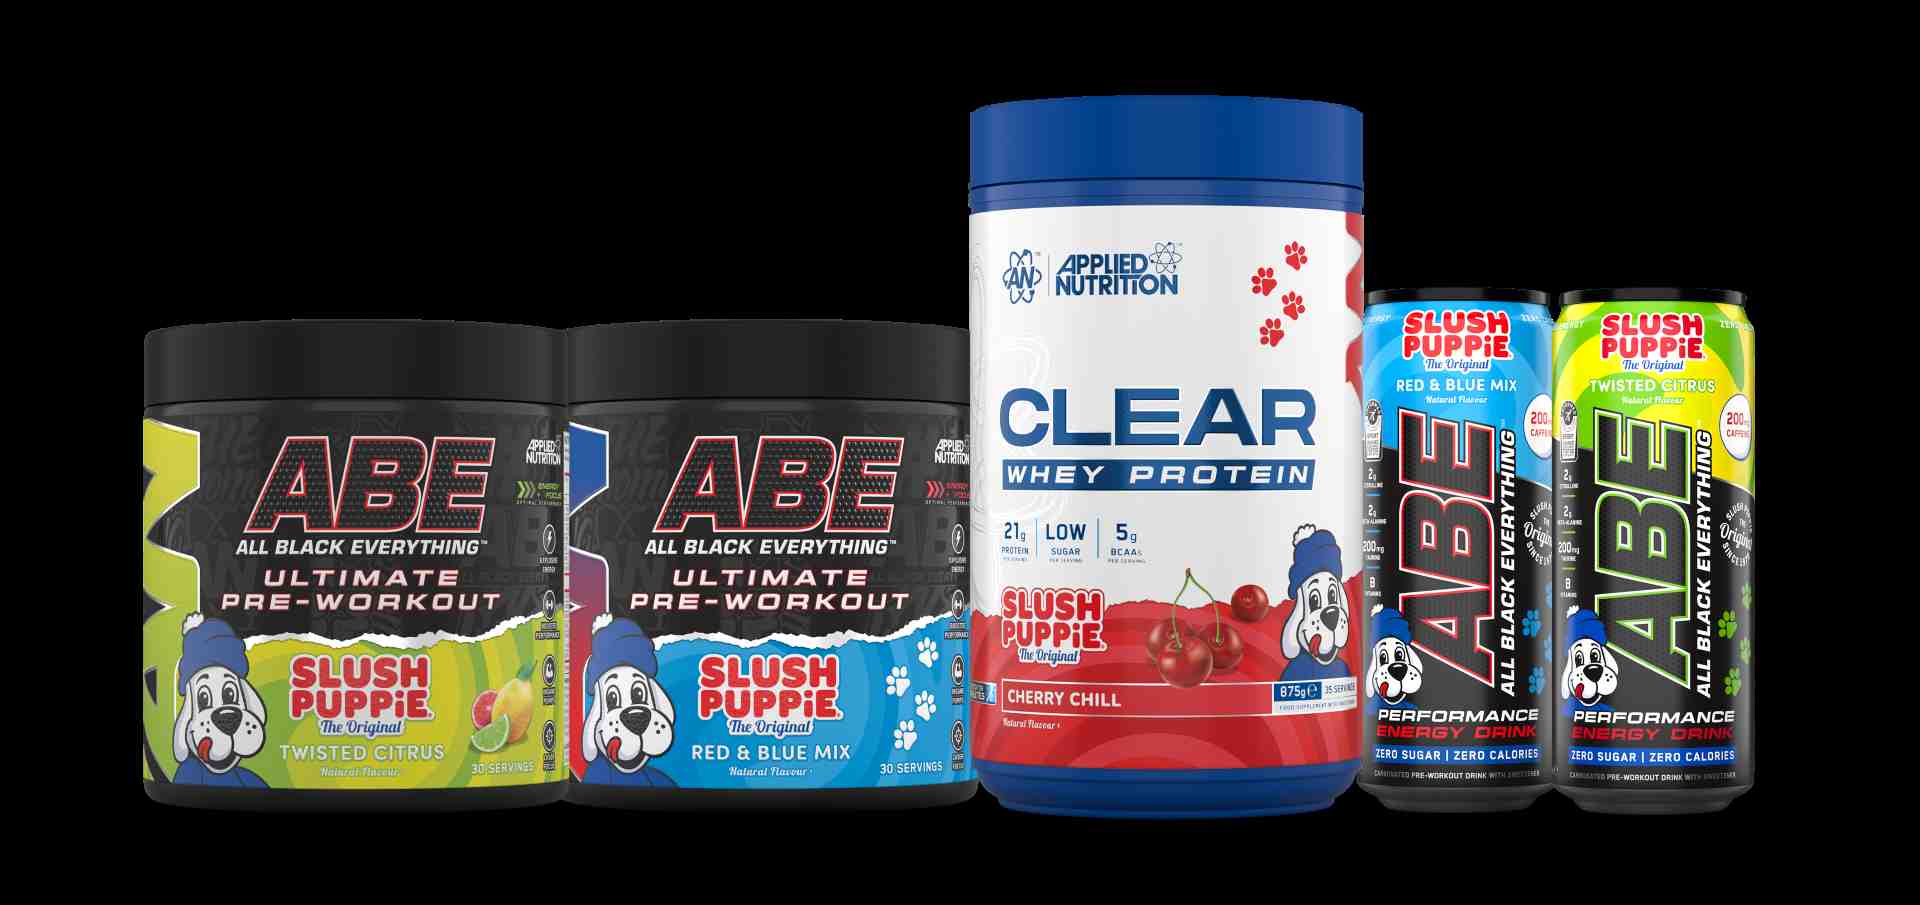
Protein powders-to-supplements maker Applied Nutrition (LON:APN) delivered stellar results for the year to July 2026, in line with recently-upgraded forecasts. In addition, the company insisted its ‘very strong momentum’ has continued into Q1 FY27, with the business winning additional market share across key channels.
However, shares in the sports nutrition brand fell as management stopped short of upgrading guidance again, prompting profit-taking by investors.
Applied Nutrition also reminded investors they can expect to see a slight decrease in margins this year. This reflects ‘significantly higher’ whey protein costs and an increased revenue contribution from the US, where margins are currently lower.
Outstanding growth
FY26 results showed a 50.9% sales surge to £161.6 million and a 40.1% jump in adjusted EBITDA to £43.3 million. Adjusted pre-tax profits bulked up 39.1% to £42 million.
Growth was generated across all regions and product ranges as the Liverpool-based firm continued to win with retail customers and consumers.
By region, UK sales grew 45.2% to £70.3 million, while Europe revenue increased 34% to £20.9 million and the Rest of World region grew 63% to £70.4 million.
Management is taking a cautious approach to FY27 guidance. Applied Nutrition confirmed that it still expects to deliver revenue of roughly £205 million and about £49 million in adjusted EBITDA, representing growth of 26.9% and 13.2% respectively.
Positive momentum
‘We have entered FY27 with very strong momentum,’ said CEO Thomas Ryder. ‘We have never been short of ambition, but our focus remains simple: make great products, move quickly and keep earning the trust of our customers and consumers.’
Ryder added: ‘With a growing global brand, expanded international capabilities, channel expansion and significant opportunities ahead, I am excited about what comes next and confident in our ability to deliver continued growth.’
Scope for upgrades
Following the results, Cavendish increased its price target from 355p to 380p: ‘Management has maintained guidance and we have left our estimates unchanged,’ explained the broker.
‘However, we can see scope for upgrades as we move through FY27 if momentum continues at pace and Applied Nutrition is able to beat some very strong comparators, particularly in the first half.’
| Year to 31 July | FY26A | FY27E | FY2E |
| Revenue (£m) | 162 | 206 | 226 |
| Pre-tax profit (£m) | 42 | 48 | 53 |
| EPS (p) | 12.5 | 14.1 | 15.6 |
Source: Company accounts, Deutsche Numis estimates
Deutsche Numis reiterated its Buy rating and upgraded its price target from 350p to 370p. The broker commented: ‘We think that Applied Nutrition continues to materially progress in executing its longer-term growth ambitions. The business continues to demonstrate sustained revenue momentum underpinned by structural category growth and strong strategic execution.’
We remain bullish about Applied Nutrition. Under Ryder’s leadership, the company is building a global sports nutrition business and tapping into consumers increasing interest in health, wellness and fitness. The Global Wellness Institute projects the global wellness economy is expected to reach nearly $9.8 trillion in 2029.
Sharesify is particularly excited by Applied Nutrition’s has growth potential in North America, where it recently completed the acquisition of Nutrablend. With US$300 million of revenue production capacity, Nutrablend provides Applied Nutrition with a platform for growth in the US.
We also think the company’s licensing agreement with snacks giant Mondelez (NASDAQ:MDLZ) to develop products under the Sour Patch Kids and Swedish Fish brands for the US and Canada could prove lucrative. Early indications from the launch of Sour Patch Kids into 2,200 Walmart (NASDAQ:WMT) and 1,300 GNC stores have been encouraging.
