

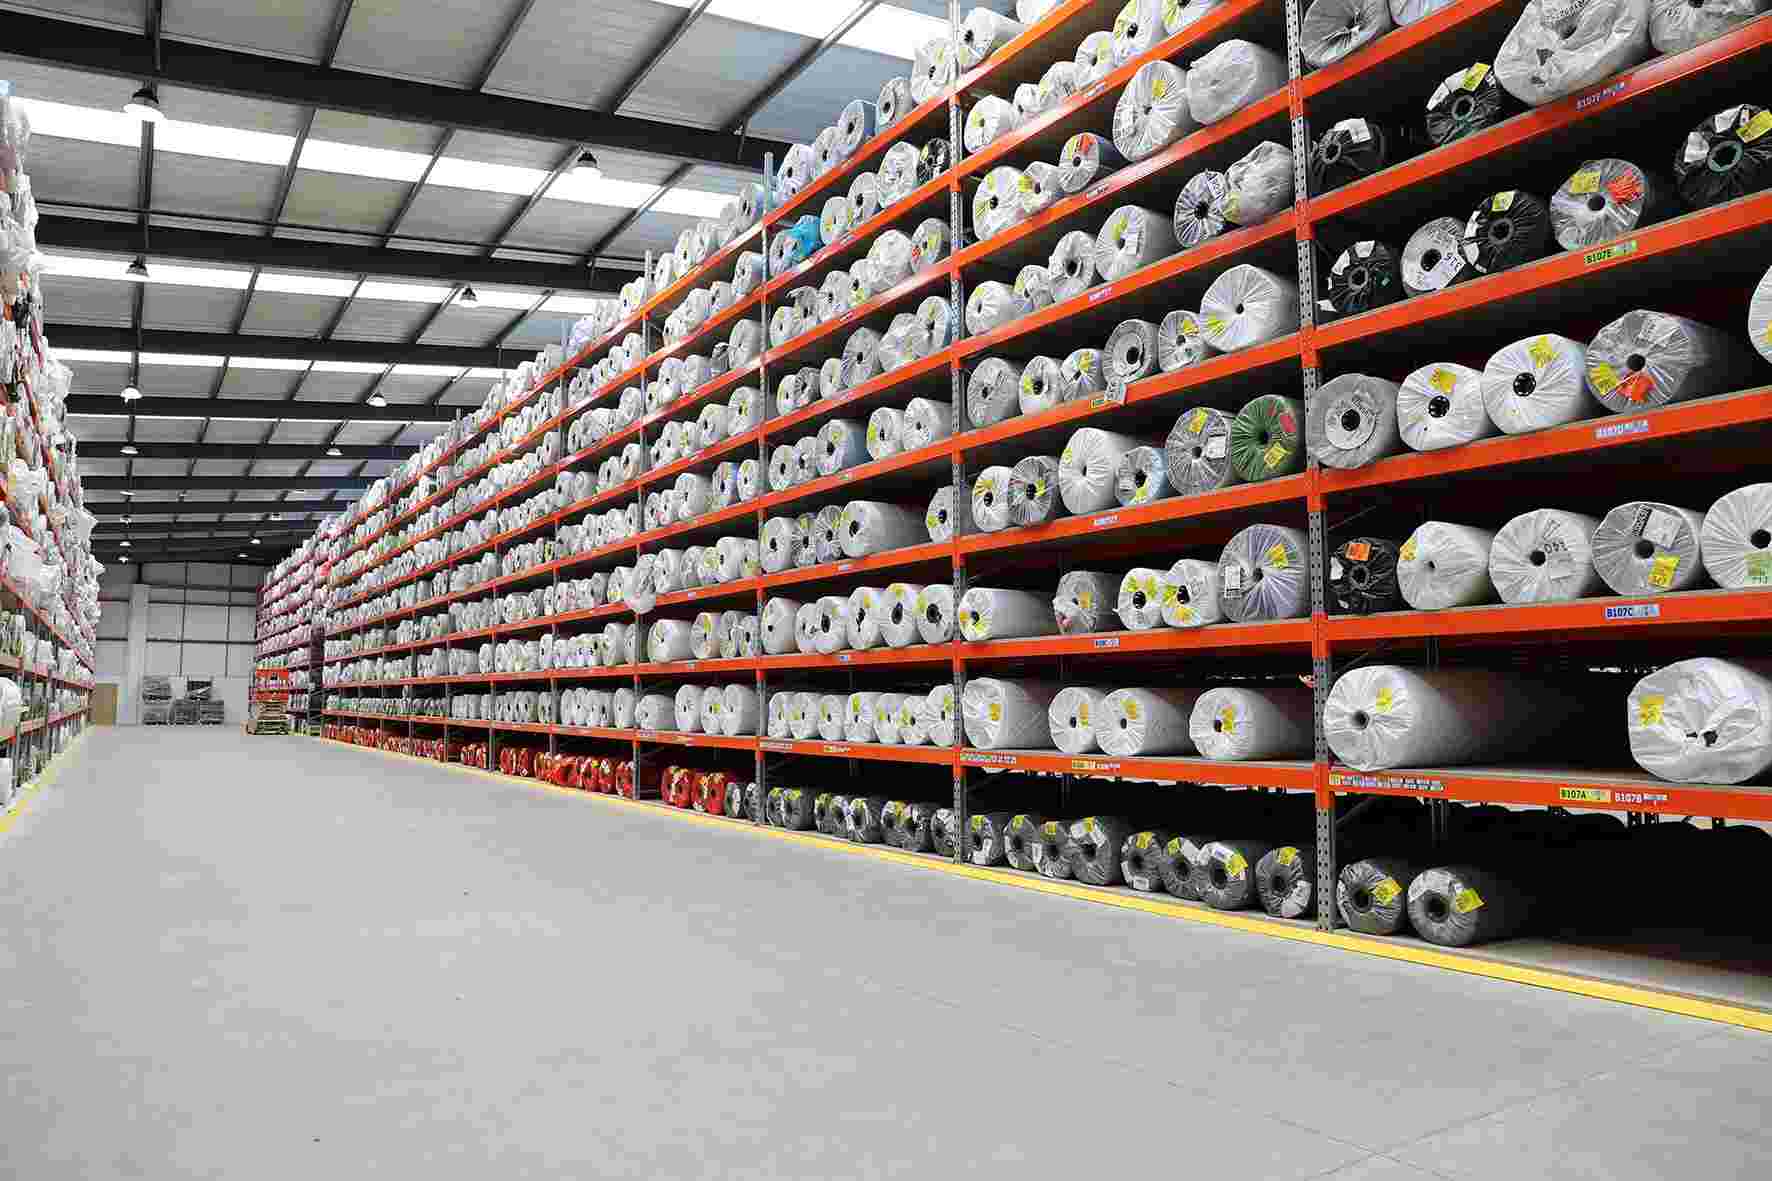
Shares in Likewise (LON:LIKE) rose after the fast-growing floor coverings distributor upgraded FY26 profit guidance following strong Q3 trading. Led by CEO Tony Brewer, Likewise continues to take market share in a tough flooring market.
And the Solihull-headquartered firm has investment in place to support a renewed medium-term £300 million revenue target, a step up from the previously stated £250 million.
On a roll
Helped by price increases, H1 results demonstrated strong revenue growth and margin improvement despite Middle-East-related cost pressures and hot UK weather. Total revenue increased 15.4% to £89.9 million and underlying pre-tax profits powered ahead by 79.5% to £1.32 million.
Cash-generative Likewise also lifted the H1 dividend by 20% to 0.165p.
Likewise reported continued strong trading into H2, with Q3 sales growth accelerating to almost 30%. As a result, underlying pre-tax profits for FY26 are now expected to be ‘materially ahead of current market expectations at not less than £5 million’. That implies impressive year-on-year profit growth of at least 60%.
What did Brewer say?
‘The group has performed strongly throughout the first half and then accelerated into the summer and early Autumn,’ explained Brewer. ‘As a result, we now expect to deliver results for the full year materially ahead of market expectations.’
Brewer added: ‘This is a result of the extensive product development, sales and marketing activities over the last few years, supported by the enlarged logistics network.’
| Year to December | FY26E | FY27E |
| Revenue (£m) | 197 | 210.3 |
| Adjusted pre-tax profit (£m) | 5 | 6.4 |
| Earnings per share (p) | 1.3 | 1.4 |
Source: Zeus Capital estimates
Zeus Capital upgraded its FY26 revenue forecast by 3.4% to £197 million and its adjusted pre-tax profits estimate by 25.2% to £5 million. For FY27, the broker introduced FY27 forecasts of £210 million revenue and adjusted pre-tax profits of £6.4 million.
‘With the infrastructure now largely in place to support £300 million of revenue and margins beginning to inflect, we see the current 0.8 times enterprise value to sales rating as too cheap for the flooring market’s emerging winner,’ said Zeus.
Though it operates in a low margin industry, we are fans of Likewise and have confidence in Brewer’s ability to deliver shareholder value over time.
The company has an exciting opportunity to capture a larger share of the fragmented UK flooring distribution market. Embattled competitor Headlam (LON:HEAD), where Brewer was CEO for many years, recently appointed the administrators.
And we think there is scope for further earnings upgrades to come from Likewise, with the busier Autumn trading period to come. The firm’s recent £32.5 million fundraise, together with the group’s banking facilities, provides significant financial flexibility to fuel the next phase of growth.
Furthermore, Zeus expects Likewise to move from a net debt to a net cash position of £4.8 million in FY27, as ‘strong cash generation outweighs the more moderate capital investment required following the completion of the current build-out phase’.
Disclaimer: The author James Crux has a personal interest in Likewise.