

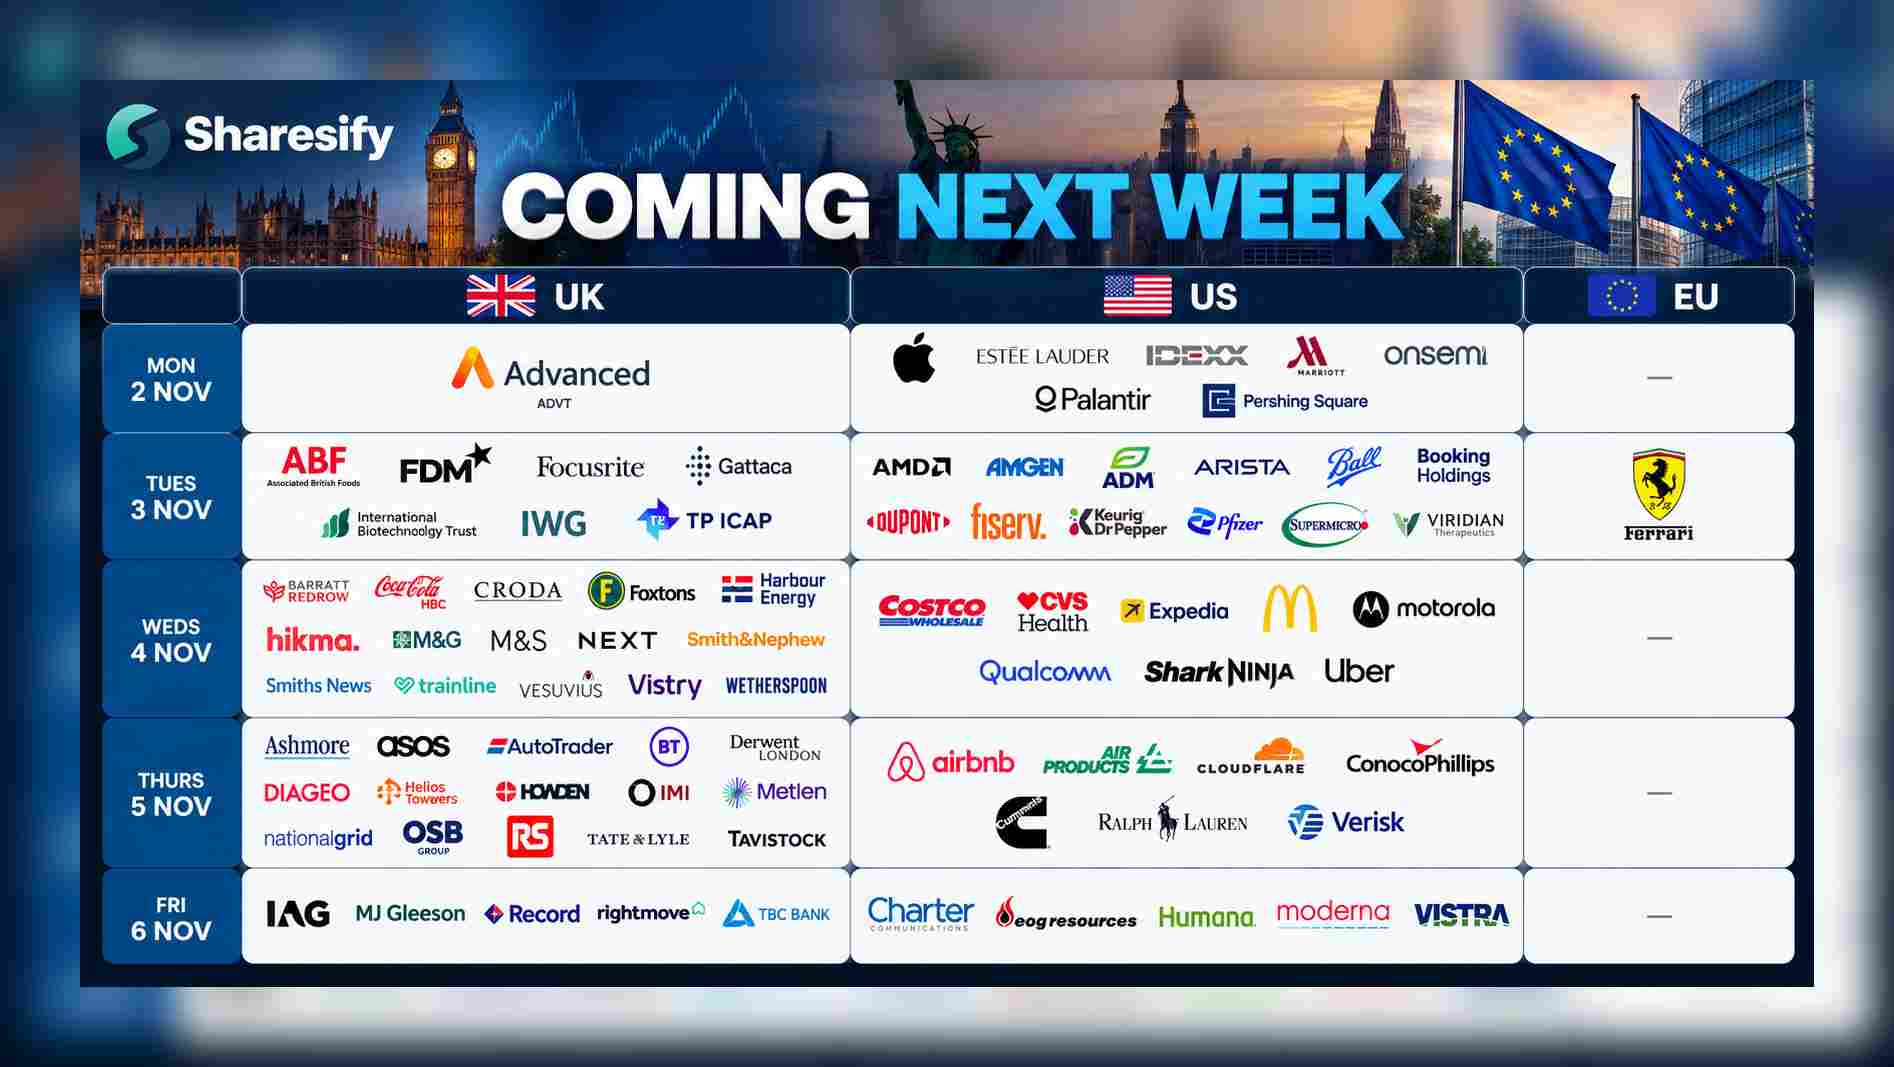
The first week of November brings a packed earnings calendar, with several heavyweight technology stocks, major UK retailers and internationally recognised consumer brands in the spotlight.
For UK retail investors, AMD, Apple, Palantir, Qualcomm and Uber are among the US names likely to attract the most attention, with investors looking for fresh clues on AI spending, semiconductor demand, cloud infrastructure and consumer resilience. Ferrari also reports on Tuesday, offering an insight into demand for luxury goods and pricing power.
Alphabet, Microsoft and KLA earnings: Is the AI trade becoming a debt-fuelled gamble?
Closer to home, Wednesday is particularly busy, with M&S, Next, Associated British Foods, Barratt Redrow, Croda, Hikma and Wetherspoons among the UK companies reporting. Thursday brings further interest from Diageo, BT, Auto Trader and National Grid, while IAG and Rightmove round off the week on Friday.
Elsewhere, investors will be watching Arista, Super Micro Computer, Costco, McDonald’s, Airbnb and Cloudflare for signals on corporate technology spending, consumer confidence and the wider economic outlook. With AI valuations, household spending and interest rates still major market drivers, there should be plenty for investors to digest.
Apple (NASDAQ:AAPL)
Apple (NASDAQ:AAPL) reports fiscal Q4 results after the US market closes on Monday, 2 November, with investors focused on iPhone sales, profit margins and the crucial Christmas-quarter outlook.
Wall Street expects revenue of approximately $113.3bn and EPS of $1.98, against $102.5bn and $1.85 respectively a year earlier. Management previously guided to 9–11% revenue growth, with iPhone sales rising at a mid-teens rate.
The biggest swing factor is likely to be December-quarter guidance. Strong demand for the latest iPhones, including the new foldable iPhone Duo, could boost expectations, but supply constraints risk limiting sales.
Consensus forecasts for Apple
| Q4 2025 | Q4 2026 | YoY Growth | Q1 2027 | |
| Revenue ($bn) | 102.47 | 113.32 | 10.6% | 153.55 |
| EPS ($) | 1.85 | 1.98 | 7% | 2.87 |
Source: Koyfin
Margins are another concern. Rising memory-chip prices threaten profitability, particularly as tariff refunds that supported previous margins may not provide the same cushion. Services growth, including subscriptions and App Store revenue, will also be scrutinised.
Finally, investors want evidence that Apple’s AI strategy can generate meaningful revenue. With a premium valuation, simply beating forecasts may not be enough: confident guidance, resilient margins and credible AI monetisation could matter more than headline earnings.
Associated British Foods (LON:ABF)
There shouldn’t be too many surprises when Associated British Foods (LON:ABF) reports its FY2026 results on Tuesday 3 November. The firm, one of the UK’s last conglomerates, already published its full-year revenue and earnings expectations in mid-September.
As usual, the focus is likely to be on the Primark retail business and current like-for-like sales trends. In Q4, UK LFLs were flat while continental European LFLs were down 4.3% leaving group sales down 3% for the quarter and 2.6% for the year.
This was partly due to the July launch of the ‘Iconic Value’ campaign across markets and catergories, with lower prices intended to ‘redefine value’. The firm said the initial volume reaction was positive and it expected to build momentum as the autumn/winter ranges hit stores.
If Primark can show an uptick in organic growth, and if the rest of the group – which includes grocery, ingredients and sugar – perks up, then investors may feel the firm has turned the corner. In its outlook, the company said it expected progress in FY2027 in spite of the impact of higher inflation on consumer sentiment.
Investors will also be hoping for an update on the Primark demerger process, which is due to happen some time next year. The business accounts for around half of group sales and two-thirds of operating profit.
Primark Q4 and FY26 LFL sales growth
| Q4 2026 | FY 2026 | |
| UK only | 0% | +0.6% |
| Uk & Ireland | +0.4% | +0.5% |
| Continental Europe | -4.3% | -4.7% |
| Primark total | -3.0% | -2.6% |
Source: Company accounts
Marks & Spencer (LON:MKS)
Investors will be hoping Marks & Spencer (LON:MKS) confirms further market share gains in the face of consumer spending headwinds when the foods-to-fashion retailer reports H1 results (4 November). Another date for the diary is the CMD (Capital Markets Day) on 10 November, where CEO Stuart Machin will set out his long-term growth strategy and capital allocation priorities for the FTSE 100 constituent.
Under Machin and chairman Archie Norman, Marks & Spencer has regained its mojo and moved from the recovery phase to a renewed focus on growth. Back in May, the retailer delivered forecast-beating FY2026 profits and said it expects profits to grow again after the disruption caused by last year’s cyber incident.
Marks & Spencer posted total sales of £17.37 billion for FY2026, up 25% on the previous year. Excluding Ocado Retail, which the company owns 50/50 with Ocado (LON:OCDO), sales rose 1.9% to £14.18 billion.
Forecasts for Marks & Spencer
| FY2027 | FY2028 | FY2029 | |
| Revenue (£m) | 19,050 | 20,203 | 21,409 |
| Adjusted PBT (£m) | 925 | 992 | 1057 |
| EPS (p) | 32.6 | 34.7 | 37 |
Source: Shore Capital estimates
The Food business has been on a roll for several years, while the Fashion, Home and Beauty business is shaking off a lingering hangover from the cyber strike. For H1, Sharesify expects Marks & Spencer will report significant market share gains and strong like-for-like growth in Food, with Ocado Retail on a growth tear. However, investors should brace themselves for a duller performance from the Fashion, Home and Beauty division.
Arch-rival Next (LON:NXT) recently moderated its UK sales growth guidance, citing rising inflation, higher mortgage interest costs, and a weak employment market, as well as the potential for future tax increases. And Shore Capital senses ‘store sales have been particularly hard to come by for Marks & Spencer, especially when the mercury rocketed through mid-summer’.
For H1, the broker forecasts a drop in pre-tax profits from £409 million to £389 million, reflecting challenging UK clothing market conditions but strong trading progress in Food. For FY2027, analysts Clive Black and Darren Shirley forecast a pre-tax profits jump from £671 million to £925 million, ahead of £992 million in FY2028.
Disclaimer: The author (James Crux) owns shares in Marks & Spencer.
You might also like:
