

Shares in Focusrite (LON:TUNE) firmed after the music and audio products company posted better-than-expected profits for the half ended 31 August. The H1 results provided further evidence that the AIM-listed company is tuning up for its next phase of growth.
Guided by CEO Tim Carroll, Focusrite insisted trading since the end of August has been ‘encouraging’ with healthy underlying demand across its Content Creation and Audio Reproduction divisions.
Accordingly, Focusrite remains confident in achieving market expectations for the year to February 2027. Consensus calls for sales of £170.1 million to £173.7 million and adjusted operating profit in the £15.6 million to £17.5 million range.
Finding its rhythm
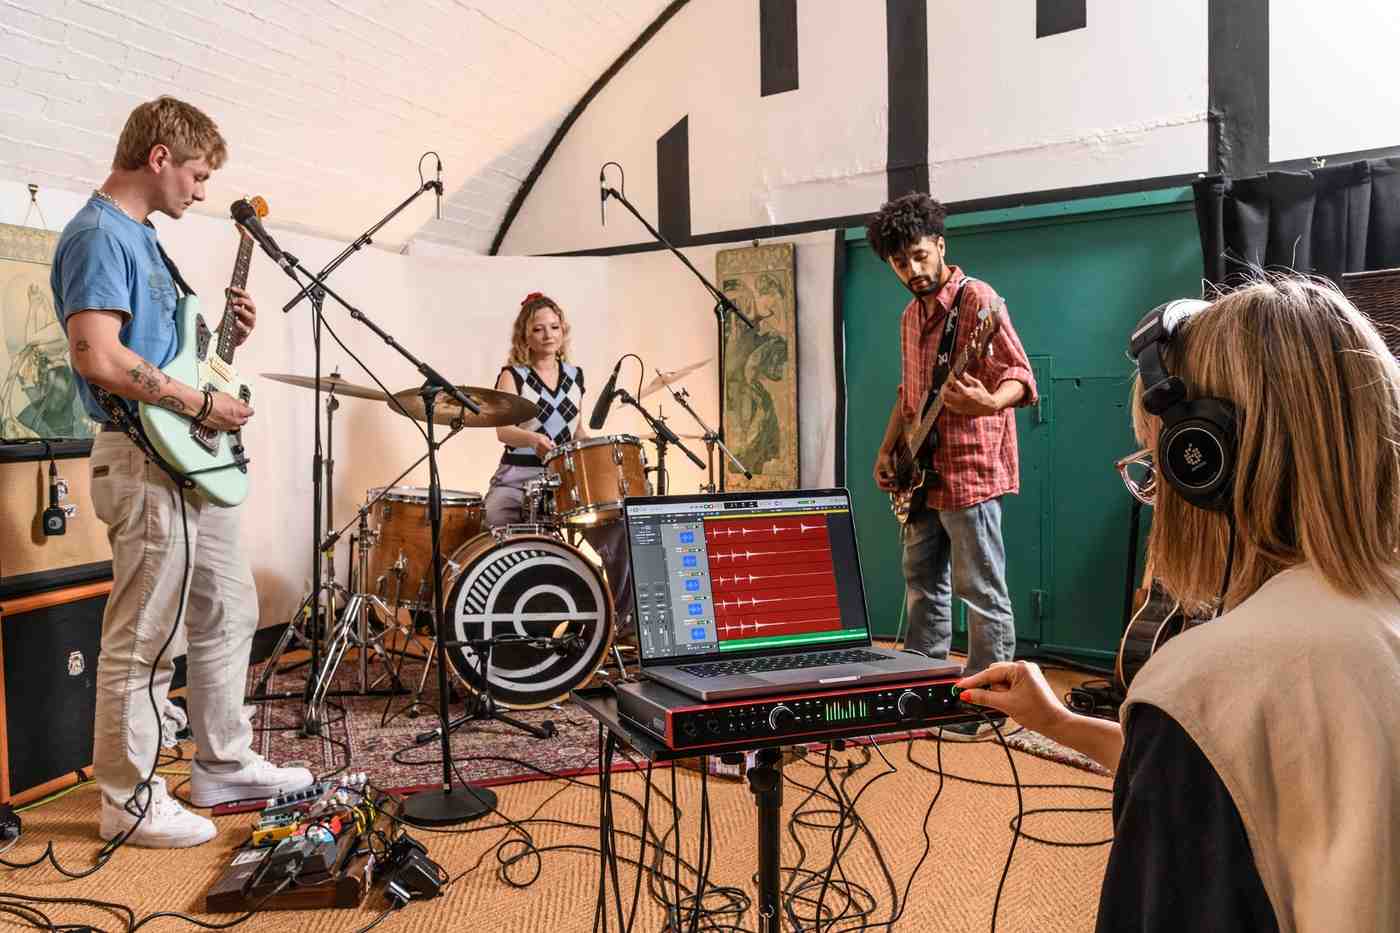
For the uninitiated, Focusrite supplies hardware and software used by professional and amateur musicians and the entertainment industry. Its products range from audio interfaces and preamps to speakers. And the firm’s solutions facilitate the high-quality production of recorded and live sound.
| Year to February | FY27E | FY28E | FY29E |
| Revenue (£m) | 170.6 | 179.1 | 188 |
| Adjusted PBT (£m) | 14.2 | 18 | 20.8 |
| EPS (p) | 17.8 | 22.7 | 26.1 |
Source: Cavendish estimates
Positive H1 results showed a modest 2.7% uptick in revenue to £90.3 million. However, adjusted operating profit grew almost 15% to £11.1 million, demonstrating the operational gearing in the business model.
How to invest in technology stocks: A UK beginner’s guide 2026
Revenue grew 5.2% to £66.9 million in the Content Creation division, supported by new product launches. In Audio Reproduction, double-digit growth in the US market was offset by a reduction in China, but the division has delivered strong growth in orders with a positive book to bill ratio for H1.
Focusrite also highlighted the ‘significant progress’ it has made with its proprietary audio silicon chip technology. The first product incorporating the technology is expected to ship in early 2027, supporting future innovation and margin enhancement.
Solid foundation for growth
Carroll commented: ‘Overall, these results reflect the progress we have made in recent years through investment in product innovation, improved routes to market and greater operational efficiency, with the business moving out of a period of adjustment to one of delivery, providing a solid foundation for future growth.’
Focusrite struggled after the pandemic-inspired boom in demand for its products faded. But the company is now back on the front foot with a focus on growth in attractive global markets.
Furthermore, Focusrite is moving forward with a significantly-strengthened balance sheet. Net debt reduced by £9.3 million year-on-year to £1.5 million in H1, thanks to working capital improvements and US tariff refunds.
And given the improving momentum in the business, with growth set to accelerate in H2, FY27 estimates could yet prove conservative.
A CMD (Capital Markets Event) on 25 November, where Carroll will provide investors with further insight into Focusrite’s strategy and growth opportunities, offers the next potential upside catalyst. Following today’s well-received results, Cavendish upgraded its price target from 340p to 350p and reiterated its ‘buy’ recommendation.
