

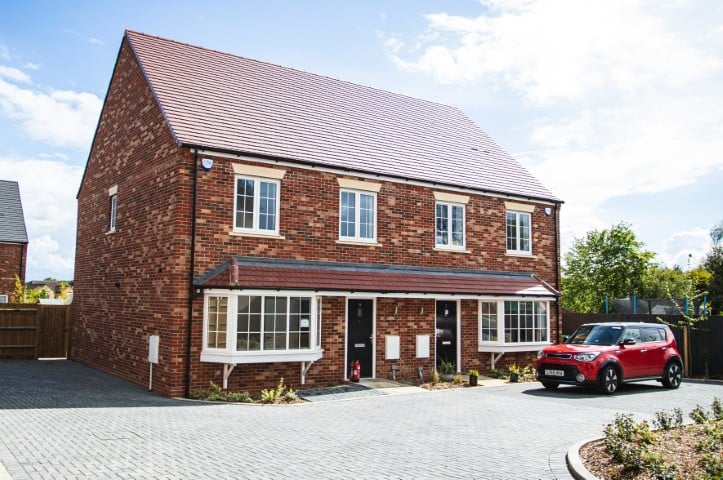
Housebuilder Taylor Wimpey (LON:TW.) cut its guidance for FY26 completions and operating profit due to the ‘challenging’ new-build market. Profit is now seen at the bottom end of the consensus range of £260 million to £300 million.
Lower FY completions and profit
For the year to December, Taylor Wimpey now expects completions to be around 10,500 homes. That compares with a consensus of 11,000 homes and a low estimate of 10,800 homes.
CEO Jennie Daly said the Autumn selling season was ‘more subdued’ as higher mortgage rates and living costs reduced affordability. Year to date, net private sales per outlet per week excluding bulk deals are 0.62 units against 0.68 units last year.
For H2 to date, the net private sales rate is even lower at 0.54 units per outlet per week against 0.61 units last year. Therefore, the current order book is lower by volume and by value than at the same point a year ago.
We aren’t remotely surprised by today’s announcement, given the continued headwinds facing housebuilders and first time buyers. Net private reservations are well down on last year, particularly in H2, and Daly also warned of softness in pricing.
Given the lower guidance, analysts will have no choice but to cut their forecasts. By extension they will likely cut their short-term price targets as well.
The ‘Your New Homes’ scheme for first time buyers is clearly positive, but it doesn’t start until next Spring. Ironically, the delayed rollout may have made the current situation worse by encouraging buyers to hold off.
We note brickmaker Forterra (LON:FORT) also cut guidance today as the stalled new-build market impacts its sales and earnings. As we’ve said before, when the recovery finally comes there will plenty of opportunity to get involved but for now there are better returns elsewhere.
