

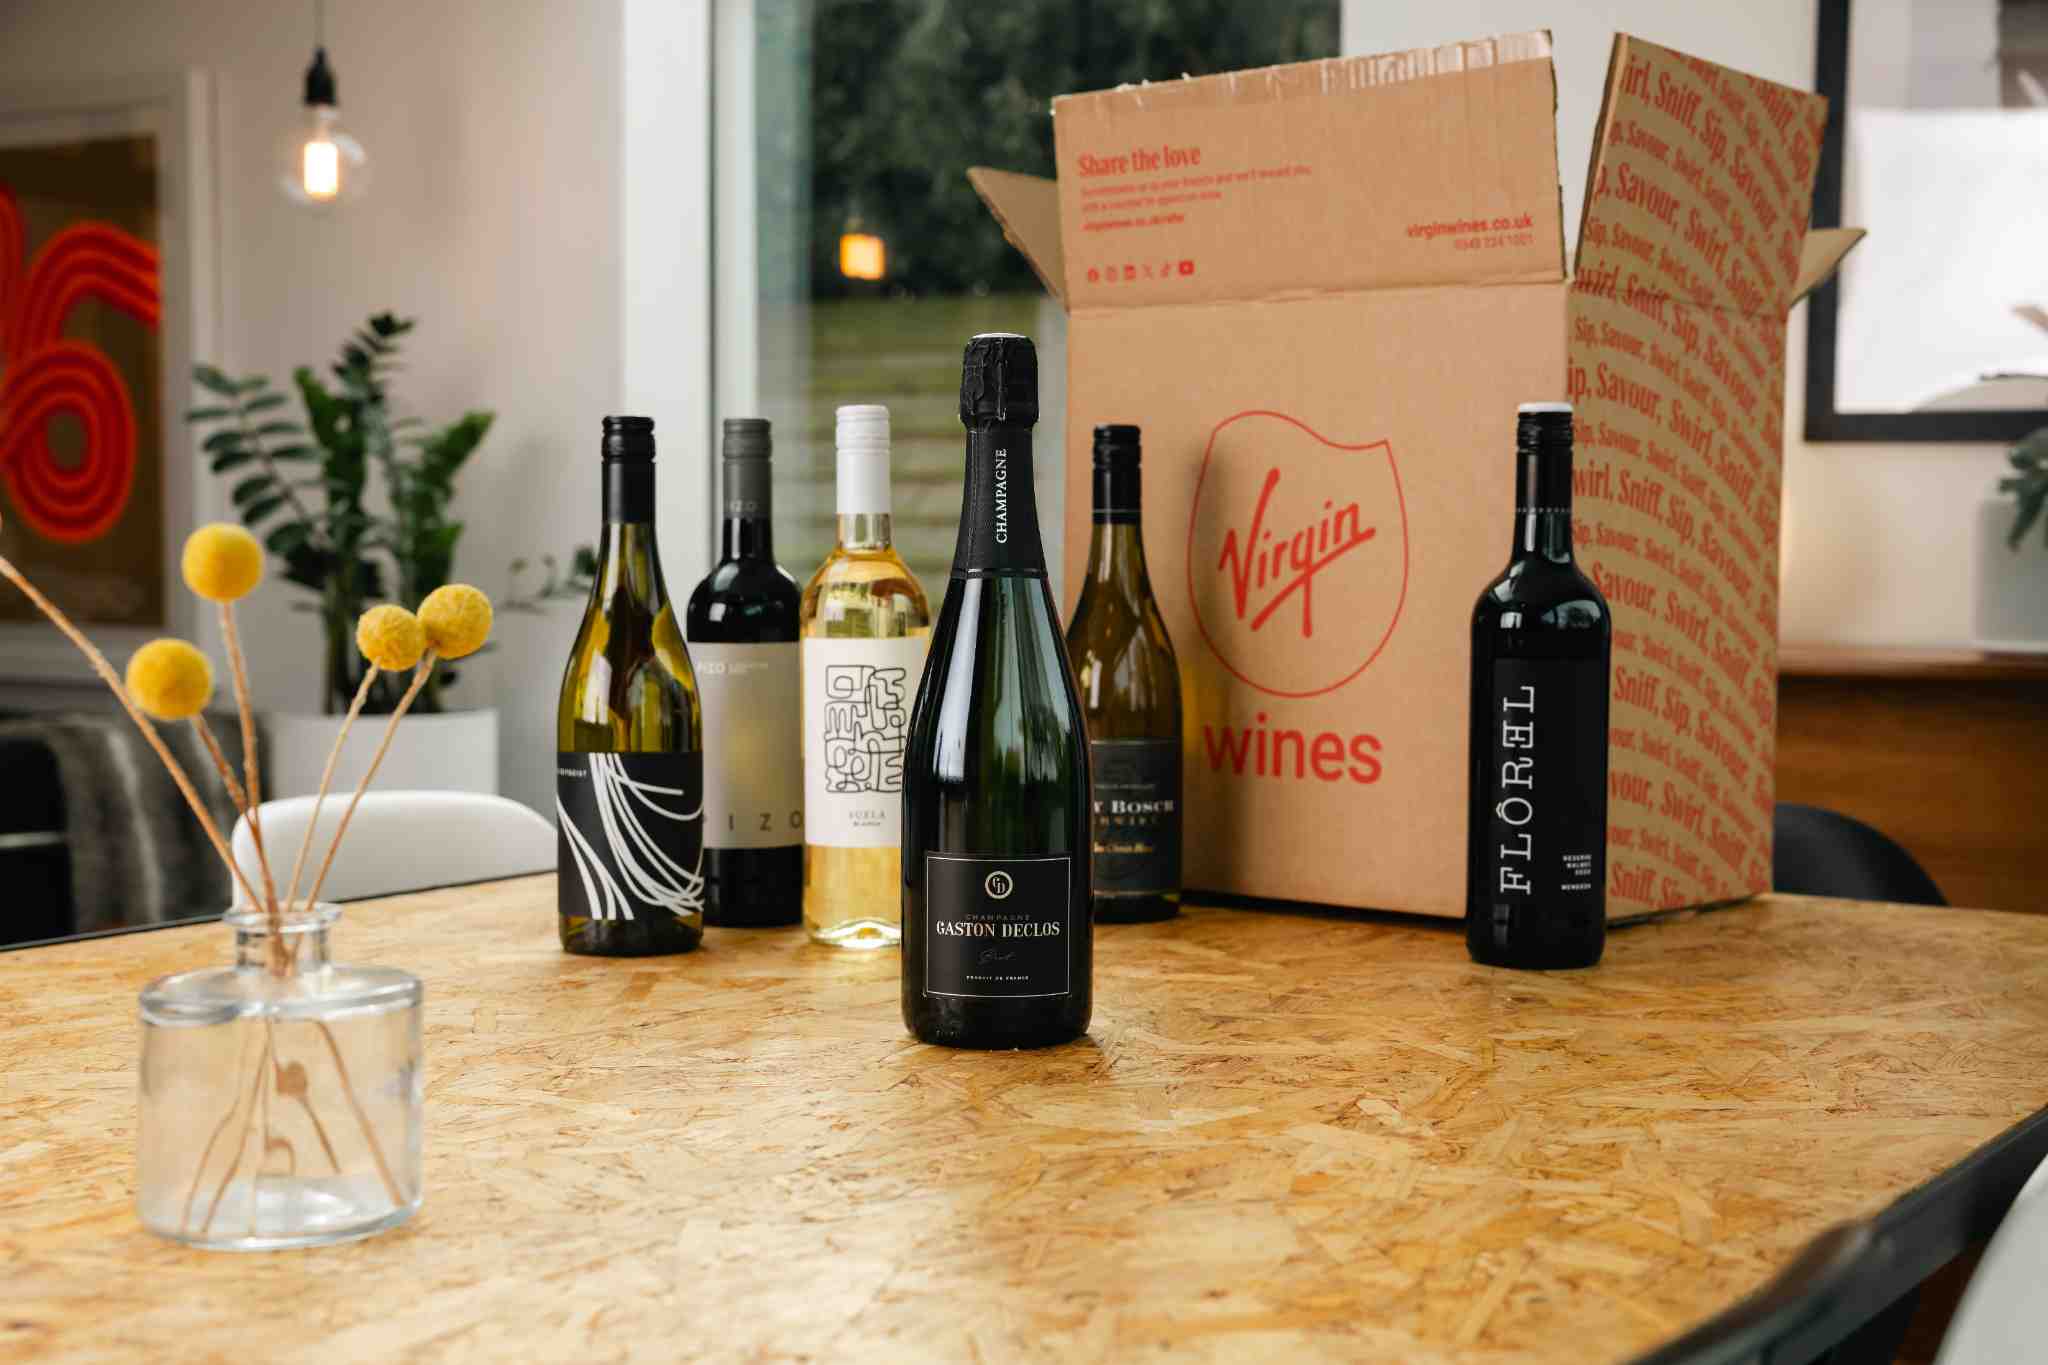
Shares in Virgin Wines (LON:VINO) rallied after the online wine retailer reported a return to growth and ‘significant’ market share gains in a challenging FY26. Results for the year ended 3 July demonstrated that CEO Jay Wright’s multi-year growth strategy is gaining traction.
The direct-to-consumer wine supplier has made a ‘positive start’ to trading through Q1 FY27 with revenue up 4.5% year-on-year. And Wright believes his charge is ‘uniquely positioned’ to capitalise on the significant opportunities ahead of it in the online drinks sector.
Return to growth and share gains
Revenue increased by 3.4% to £61 million in FY26, representing a return to growth for Norwich-headquartered Virgin Wines. The specialist wine supplier outperformed the wider online drinks market, which declined during the period.
As expected, Virgin Wines swung from pre-tax profits of £1.6 million to losses of £1.5 million due to the increased investment in its refreshed growth strategy, cost pressures and a challenging consumer environment. However, this investment is driving improved customer acquisition, which should underpin future improvements in profitability and free cash flow generation.
Forecasts for Virgin Wines
| FY27E | FY28E | FY29E | |
| Revenue (£m) | 68.5 | 75.9 | 84 |
| Adjusted pre-tax profit (£m) | -1.0 | 0.3 | 2.5 |
| EPS (p) | -2.0 | -0.34 | 3.6 |
Source: Cavendish estimates
FY26 highlights included a 41% jump in customers acquired across the group and strong growth in the Warehouse Wines business. Virgin Wines’ existing commercial partnerships with Moonpig (LON:MOON) and Ocado (LON:OCDO) also performed well.
And the AIM-listed company is exploring new partnerships within UK sports stadiums. This should open up another exciting growth channel for Virgin Wines.
What did Wright say?
Wright commented: ‘Despite a challenging consumer environment and significant cost pressures across the sector, we returned the business to growth after three years of flat like-for-like sales, with revenue increasing by 3.4% to £61 million and significant market share gains, in sharp contrast to the performance seen across the wider sector.’
He added: ‘Importantly the investments we are making are delivering results. We saw strong growth in customer acquisition with 41% more customers acquired, Warehouse Wines grew revenue by 92% to £3.45 million, our commercial partnerships continued to develop, and early indications are that our new mobile app is performing strongly.’
Having returned to growth, Virgin Wines looks a tasty recovery play for patient small cap investors. The company is reaping the benefits of its new growth strategy and is well-set for the important Christmas quarter.
Crucially, Virgin Wines’ net cash balance sheet provides the group with the flexibility to continue investing in its next phase of growth. A planned move to a single distribution centre in Preston will support savings and efficiency gains from FY28 onwards.
Following today’s encouraging results, Cavendish reiterated its buy recommendation and 75p target price for Virgin Wines. That implies palate-pleasing upside of 180% from current lowly levels.
