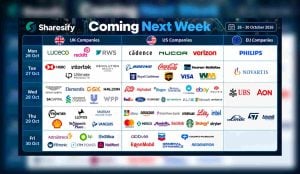


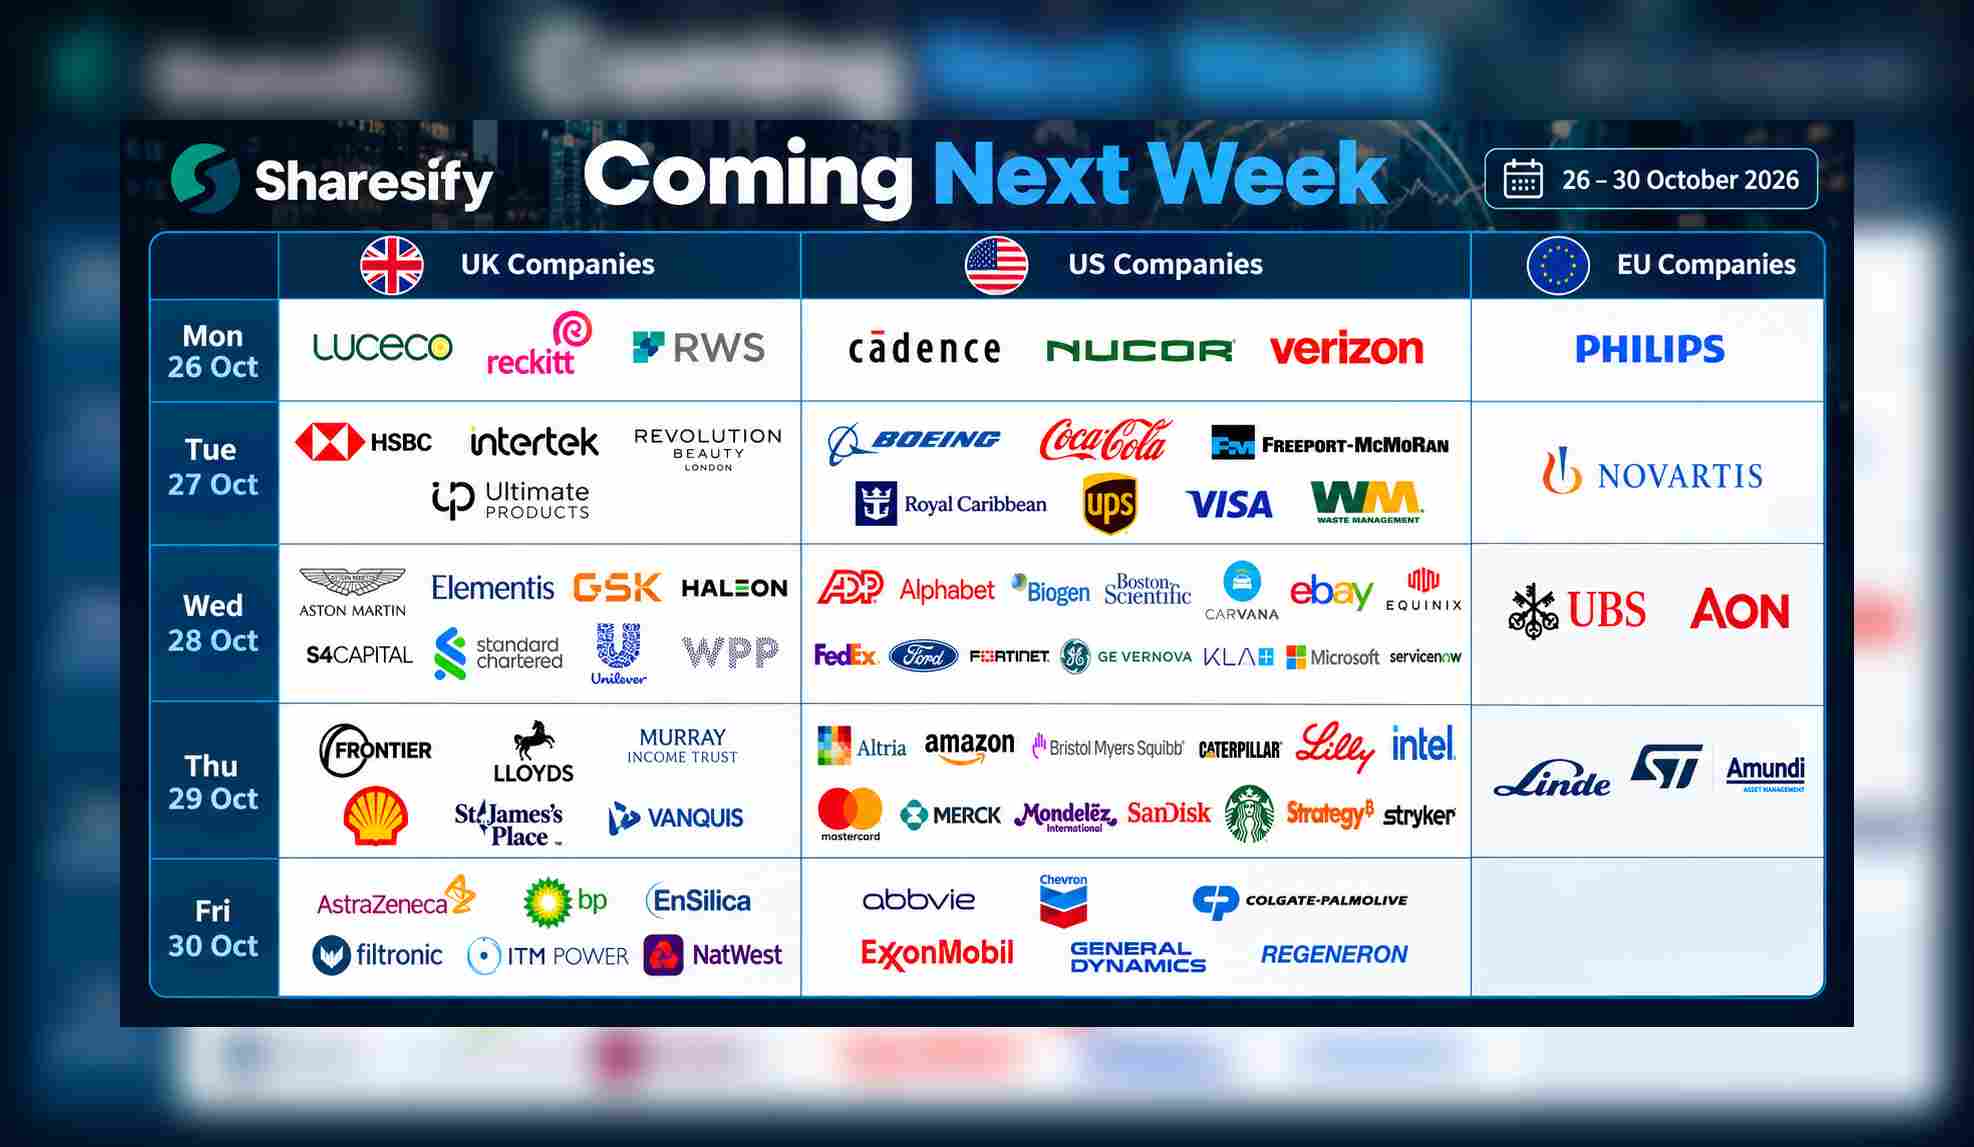
The week of 26–30 October 2026 is set to be one of the busiest earnings periods of the quarter, giving UK retail investors plenty to digest across banks, healthcare, energy, consumer stocks and technology. In the UK, HSBC, GSK, Unilever, Shell, Lloyds, AstraZeneca and NatWest are among the biggest reports, while Aston Martin and Haleon offer more focused reads on consumer demand and company-specific execution.
The real global market focus, however, is likely to be in the US. Alphabet and Microsoft report on Wednesday, followed by Amazon, Eli Lilly, Intel, Mastercard and SanDisk on Thursday. Visa, Boeing, Caterpillar and others add further important signals on consumer spending, industrial demand and global trade.
For investors watching the AI trade, Microsoft, Alphabet, Amazon, Intel, SanDisk and KLA could provide particularly important clues on cloud spending, semiconductor demand and AI infrastructure investment.
The AI trade: What SpaceX and Super Micro earnings signal to investors
Coca-Cola (NYSE:KO)
Shares in Coca-Cola (NYSE:KO) have fizzed up 35% year-to-date on forecast-beating earnings, FY26 guidance upgrades and market share gains, in part from arch-rival PepsiCo (NASDAQ:PEP). The beverages behemoth has also benefited from a flight to quality, with a more volatile market backdrop making investors thirsty for defensive mega caps. One of Warren Buffett’s most famous investments, Coca-Cola is a ‘Dividend King’, having increased its dividend for 64 consecutive years.
Investors will be hoping the total beverage titan serves up strong Q3 results on 27 October. A positive update on organic growth and market share gains, or another boost to FY2026 guidance, could send the stock price higher on results day. Analysts will also be keen to hear CEO Henrique Braun’s thoughts on the outlook for inflation and the staying power of the US consumer.
In July, the Atlanta-based giant delivered strong Q2 results showing 6% organic sales growth. Unit case volume was up 5%, led by India, China, the US and Brazil and boosted by marketing around the FIFA World Cup.
Consensus forecasts for Coca-Cola
| Q3 2026 | FY 2026 | FY 2027 | |
| Revenue ($bn) | 12.9 | 49.8 | 49.8 |
| EPS ($) | 0.88 | 3.31 | 3.53 |
Source: Investing.com, Stockopedia
‘While we continue to see a dynamic consumer landscape, we leveraged our powerful brands and system to gain value share, delivering revenue, profit and earnings growth while also investing for the long term,’ said Braun.
Coca-Cola raised its FY2026 guidance for organic growth, free cash flow and EPS (earnings per share), the latter to a 9% to 10% range. For Q3, Wall Street expects revenue of $12.9 billion, implying year-on-year growth of 4%-plus, and EPS in the $0.87 to $0.88 range.
Reckitt Benckiser (LON:RKT)
Consumer health and hygiene group Reckitt Benckiser (LON:RKT) delivered an upbeat H1 report at the end of July. Investors will therefore be hoping that positive momentum has carried through into Q3 when the firm reports on Tuesday 27 November.
At the top line, like-for-like net revenue growth for the core business accelerated from 1.3% in Q1 to 4.2% in Q2. Excluding Russia Hygiene, which is being divested before the year-end, core Reckitt LFLs were up 4.9% in Q2
Growth was balanced with volumes up 2% in the core business, pricing up 1.3% and product mix contributing a 0.9% uplift. Thatr compared with volumes down 1% in Q1, and a similar combined price/mix contribution.
The firm said the recovery in volumes was led by new innovations in its Powerbrands such as Dettol, Durex and Mucinex. Dettol Activ Botany sales are exceeding expectations in China, while Mucinex 12HR Cold & Fever sales are ramping up ahead of flu season.
Reckitt is going through a big corporate change this year with the divestment of its Essential Home division and the Russian business. Meanwhile its Fuel for Growth programme is reducing fixed costs, driving efficiency and freeing up capital for reinvestment.
Reckitt 2026 LFL net revenue growth by quarters
| Q1 2026 | Q2 2026 | H1 2026 | |
| Group | +0.6% | +4.7% | +2.6% |
| Core | +1.3% | +4.2% | +2.7% |
| Price/Mix | +2.3% | +2.2% | +2.2% |
| Volume | -1.0% | +2.0% | +0.5% |
Source: Company data
Assuming sales see continued positive momentum, we are hopeful the firm will not just confirm FY guidance but nudge it higher. Although the shares have had a nice move this month they are still down 10% for the year and are well below our £75 target price.
Disclaimer: The author (Ian Conway) owns shares in Reckitt
SanDisk (NASDAQ:SNDK)
For UK retail investors, SanDisk’s (NASDAQ:SNDK) outlook for NAND pricing and AI-driven data-centre demand is likely to matter more than simply whether quarterly earnings beat forecasts. The company reports fiscal Q1 2027 on 29 October, with management already guiding to $10.3bn-$10.8bn of revenue.
The key question is whether the extraordinary memory-price upcycle can continue. In the previous quarter, revenue reached $8.97bn, up 51% sequentially, with roughly two-thirds of the increase coming from higher pricing. YoY growth is predicted to be nothing short of spectacular. Investors will therefore scrutinise average selling prices, gross margins and supply/demand commentary for evidence that pricing power remains intact.
| Q1 2026 | Q1 2027 | YoY Growth | Q2 2027 | |
| Revenue ($bn) | 2.31 | 10.68 | +362% | 12.21 |
| EPS ($) | 1.22 | 46.27 | +3,693% | 52.94 |
Source: Koyfin
AI is another major catalyst. SanDisk has highlighted growing demand from data-centre customers, while its high-bandwidth flash technology is being positioned for AI inference workloads.
How to invest in AI stocks: A UK beginner’s guide 2026
Finally, guidance for the next quarter and commentary on 2027 NAND supply discipline, enterprise demand and cash generation could determine whether the shares rebound after their recent pullback—or whether investors lock in profits.
You might also like:
