

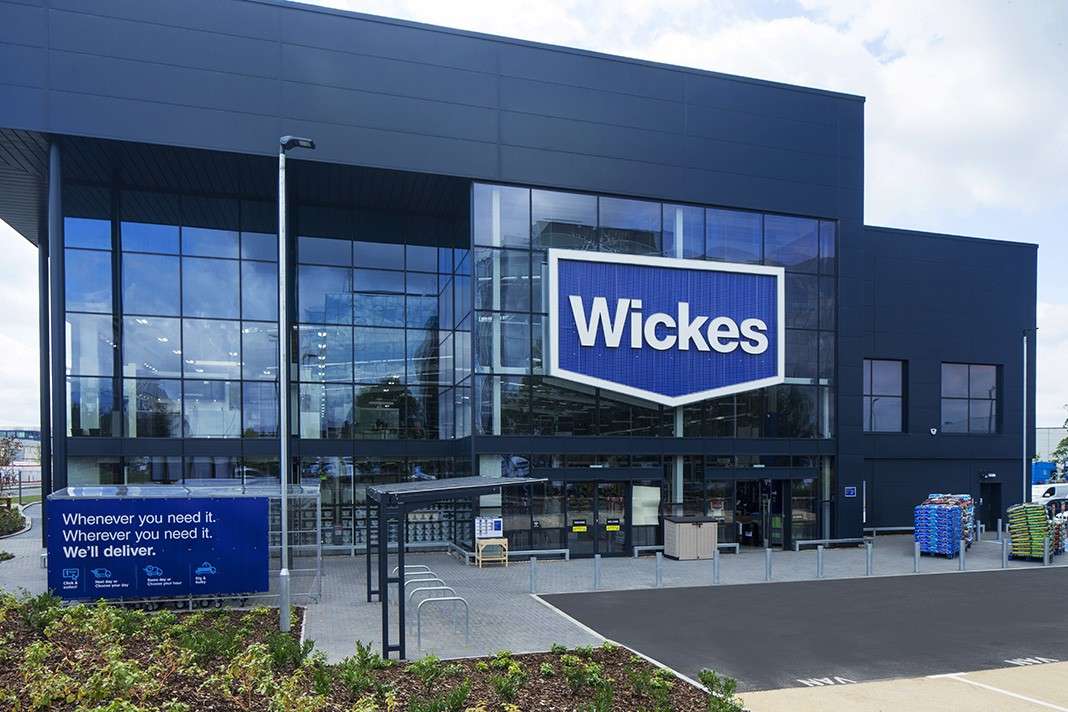
Shares in Wickes (LON:WIX) rose to a six-month high after the home improvement specialist reported a step up in retail revenue growth for the third quarter. Investors breathed a sigh of relief as Wickes insisted it remains on track to meet consensus expectations for FY26, which on average point to 10% adjusted pre-tax profit growth.
‘Our value-led and differentiated business model leaves us well-positioned to continue outperforming the market,’ said the FTSE 250 retailer.
Positive retail trend
Led by CEO David Wood, Wickes’ group revenue increased by 4.5% year-on-year to £439 million in the quarter ended 26 September. This solid performance reflected strong volume-led growth across the business.
Wickes said trading in retail saw a ‘significantly improved performance’ in Q3, with a step up to 6% revenue growth.
| Wickes – Q3 performance | Q3 2026 | |
| Retail | Revenue | £331m |
| Revenue growth | +6% | |
| Like-for-like sales growth | +5.6% | |
| Design & Installation Ranges | Revenue | £108m |
| Revenue growth | +0.3% | |
| Like-for-like sales growth | (0.6%) | |
| Group | Revenue | £439m |
| Revenue growth | +4.5% | |
| Like-for-like sales growth | +4% |
Source: Wickes, Q3 trading statement
‘Further market outperformance has led to continued market share growth, with notable strength in timber, flooring, roofing and garden,’ explained the DIY retailer. Within Retail, TradePro continued to perform well, with sales up 8% year-on-year as local trade professionals continued to choose Wickes to save them time and money.
Delivered sales in Design & Installation were broadly flat. Wickes continued to see healthy revenue and volume growth in lifestyle kitchens and bespoke bathrooms. However, customers are becoming ‘more considered’ when it comes to spending on big-ticket bespoke kitchen ranges.
Momentum across the piece
‘We’ve delivered a strong third quarter, with growth accelerating across retail as more customers choose Wickes for their home improvement projects,’ enthused Wood.
‘Our continued market share gains demonstrate the strength of our value-led proposition and our ability to outperform in a competitive market. With good momentum across the business, we remain on track to deliver market expectations for full-year profit.’
Before today’s update, the company-compiled consensus called for FY26 adjusted pre-tax profits in the £52.8 million to £56 million range with a mean of £54.7 million.
Wickes continues to showcase its resilience in the face of weak consumer confidence and a tough housing market. While the near-term outlook remain uncertain, Sharesify believes Wickes can continue to outperform competitors over the medium-to-long term while progressing its ambition to reach 300 stores.
Readers should also note the FTSE 250 retailer has a long runway for growth. Wickes has just 5% of a £35 billion total addressable market of home improvement, kitchens, bathrooms and home energy solutions in the UK.
Jefferies has a ‘buy’ rating and 250p price target for Wickes. The broker said: ‘Although the sharp Retail like-for-like acceleration should come as little surprise, we see this as an encouraging update. It clearly demonstrates the potential of a leading proposition where market shares gains continue to be made, and short-term headwinds subside. The shares remain undervalued.’
Peel Hunt maintained its 295p target price for the stock. ‘Wickes again outperformed the market in Q3, and we expect it continue doing so in the medium term,’ said the broker.
Disclaimer: The author James Crux has a personal interest in Wickes.
